 Follow Us on Google

From Adanna Nnamani, Abuja and Henry Uche
“Recapitalisation has strengthened Nigeria’s insurance industry. Now, the industry must prove that it deserves the confidence placed in it”.
That is the position of subscribers and other stakeholders in the industry.
They want insurance companies to walk their talk with regards to assurances of better services.
Their stance is accentuated by the fact that Nigeria’s insurance industry, for years, has struggled with a contradiction of a large population, a huge and growing economy and rising business risks on one hand, but relatively shallow insurance coverage and limited financial capacity among many operators on the other.
They want that equation to change.
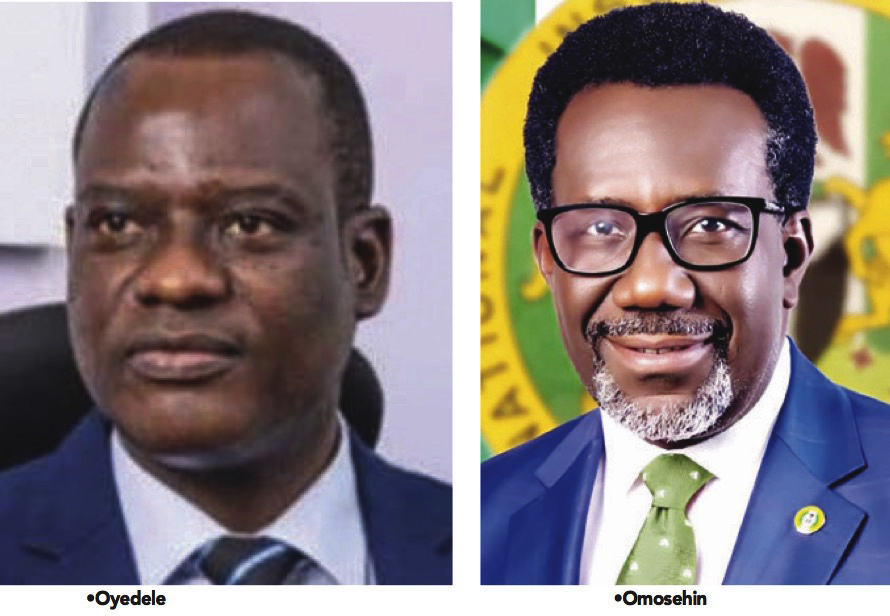
The recently concluded recapitalisation exercise has pushed the total capital of Nigeria’s insurance industry to N1.079 trillion, according to the National Insurance Commission’s (NAICOM) Chief Executive Officer, Mr Olusegun Omosehin.
The regulator said 48 insurance companies and two reinsurance firms successfully crossed the new capital threshold and were re-licensed.
The figures, experts note, represent more than an accounting milestone as it raises a bigger question around what should Nigerians, businesses, investors and the wider economy expect from a better-capitalised insurance industry.
Subscribers say the answer should go beyond bigger balance sheets.
The recapitalisation was designed to create stronger operators capable of absorbing larger risks, protecting policyholders and playing a more meaningful role in economic development.
NAICOM’s latest disclosure suggests that the industry has emerged with considerably more financial muscle. But capital is only the beginning.
From survival to capacity
One of the most immediate expectations is that insurers will now be able to underwrite risks that were previously beyond their capacity.
Nigeria is undertaking major investments in infrastructure, energy, aviation, manufacturing, telecommunications, transportation, housing and agriculture. These projects require insurance cover running into billions of naira and, in some cases, hundreds of millions of dollars.
A stronger insurance industry should therefore be able to retain more risks locally instead of transferring a large portion of them to foreign markets.
This is important because excessive dependence on foreign reinsurers means premiums generated from Nigerian economic activity can leave the country.
With stronger capital, insurers should have greater capacity to retain risks, negotiate better reinsurance arrangements and compete for major corporate accounts.
For an economy seeking to attract massive private investment, this matters.
Investors need to know that their factories, aircraft, ships, warehouses, equipment, employees and other assets can be adequately insured.
The stronger the domestic insurance industry, the greater its ability to support that investment.
Claims payment as the real test
But for ordinary Nigerians, the success of recapitalisation will not be measured by the amount of capital sitting on company balance sheets.
It will be measured at the point of loss.
A motorist in Abuja, Henry Jude, asked a key question.
If I suffer an accident, how soon will compensation come?
A businesswoman, Mrs Ijeoma Opara also asked; if my house is destroyed by fire, or my husband loses business equipment, or my brother, a farmer, suffers a major crop failure or when a family loses its breadwinner, will the insurer pay?
This is where the post-recapitalisation era must be different.
NAICOM has already identified prompt claims settlement as a priority, alongside deeper insurance penetration, financial inclusion, digital innovation and risk-based supervision.
The regulator’s challenge is to ensure that stronger capital translates into stronger consumer protection.
A company may have billions of naira in capital, but if claims are unnecessarily delayed, disputed or rejected, public confidence will remain weak.
The industry therefore needs to move from a culture of selling policies to one of delivering protection.
More mergers and stronger players
Another likely consequence of recapitalisation is a more concentrated market.
Not every operator will pursue the same strategy. Some may seek aggressive expansion, while others may specialise in particular sectors. Some may pursue partnerships or mergers.
NAICOM had made it clear that operators could raise fresh capital, merge or enter partnerships to meet the new requirements.
This could eventually produce fewer but stronger companies.
Such consolidation is not necessarily bad. A market populated by financially stronger operators may improve competition, corporate governance, technology investment and product development.
But consolidation must not create complacency or excessive market power.
The regulator will need to ensure that the emerging giants remain competitive, transparent and responsive to policyholders.
Insurance must finally reach the mass market
Perhaps the biggest opportunity created by recapitalisation is the chance to take insurance beyond Nigeria’s corporate sector.
Insurance penetration remains low, while millions of Nigerians operate businesses, own homes, drive vehicles, farm land and earn incomes without adequate protection.
The industry has traditionally struggled to convince the average Nigerian that insurance is a necessity rather than an avoidable expense. That must change.
The new capital should encourage companies to develop affordable products for low-income earners, traders, farmers, transport operators, artisans and small businesses.
Microinsurance, agricultural insurance, health-related products, life insurance and affordable property cover should receive greater attention.
Technology
The industry also needs to exploit technology.
NAICOM has indicated that it is supporting digital innovation and the growth of insurance technology companies, with more insurtech licences expected.
That is significant because digital distribution can reduce costs and bring insurance closer to people who have never walked into an insurance office.
A trader should be able to buy a simple policy with a mobile phone.
A farmer should be able to insure crops digitally.
A small business owner should be able to obtain property and liability cover without navigating complicated paperwork. Capital must be put to work. There is also a danger.
The recapitalisation could become a cosmetic exercise if the additional capital simply strengthens balance sheets without producing better underwriting, investment and customer service.
The industry must therefore demonstrate what it intends to do with the new money.
Capital should support technology, skilled manpower, stronger risk management, product innovation, distribution networks and the ability to absorb larger risks.
Insurers must also maintain sound asset quality and avoid taking excessive investment risks in pursuit of quick returns.
This makes NAICOM’s shift towards risk-based supervision particularly important.
The regulator cannot simply check whether companies meet minimum capital requirements. It must continuously examine the quality of capital, solvency, governance, underwriting practices, investment decisions and ability to meet claims.
Bigger role in Nigeria’s economy
The recapitalised industry also has an opportunity to become a much bigger source of long-term finance.
Insurance companies collect premiums today against risks that may materialise years later. Properly managed, these funds can support long-term investments.
That could make the industry an important player in infrastructure financing, capital markets and economic development.
The opportunity is particularly important as Nigeria seeks to expand investment and move towards a much larger economy.
But insurers must resist the temptation to chase size for its own sake.
The objective should be sustainable growth.
An immediate development to watch is the release of the newly raised capital.
The funds are currently held in escrow with the Central Bank of Nigeria for verification. NAICOM has indicated that successful operators should be able to access the funds by September 30, 2026. That will mark the beginning of the next phase.
Other News
The difficult work is no longer about raising capital.
It is about proving that the capital can produce value.
The insurance industry now has the financial foundation to write bigger risks, serve more customers and contribute more substantially to Nigeria’s economic growth.
As experts noted, what Nigerians should expect next are better products, faster claims, stronger companies, wider coverage and greater accountability.
According to them, the N1.079 trillion capital base is impressive. But the real measure of recapitalisation will be how much of that strength eventually finds its way into the pockets of policyholders, the balance sheets of businesses and the productive sectors of the Nigerian economy.
NAICOM’s 6-point ISSP plan
The regulator recently unveiled the Insurance Sector Strengthening Programme (ISSP) as the vehicle for taking the industry into what it describes as a more inclusive, innovative, resilient and trusted future.
The programme seeks to increase insurance penetration from about 0.5 per cent of Gross Domestic Product (GDP) to 1.5 per cent by 2028, while working towards a much larger market in subsequent years.
Central to the ISSP are six major areas: advocacy and policy, awareness and education, capacity building, gender inclusion, youth engagement, and Micro, Small and Medium Enterprises (MSMEs) and value-chain development.
Put simply, NAICOM wants more Nigerians to understand insurance, buy insurance and benefit from it.
The scale of the ambition is significant.
According to the ISSP executive summary, only about five per cent of Nigerians currently have insurance coverage, while 78 per cent lack basic insurance knowledge. Women account for about 32 per cent of policyholders, people aged 18 to 35 represent less than 20 per cent of the customer base, while insurance penetration among MSMEs is estimated at only eight per cent.
The programme, therefore, plans to reach five million members of the general population, two million women entrepreneurs and decision-makers, 1.5 million young Nigerians and 250,000 MSMEs across the country.
The targets have generated cautious optimism among industry experts.
For Dr. Obinna Chilekezi, an insurance researcher, consultant and teacher of insurance and risk management, the ISSP is a welcome development, particularly because Nigeria’s insurance penetration has remained below the African average for years.
He believes the emphasis on advocacy, awareness and capacity building could create the right environment for the sector to grow.
“I feel looking at the targets, one could say that it is a laudable one, taking into consideration the fact that our insurance penetration over time has been far below African average,” he said.
According to him, inclusive insurance could help the Commission achieve its objectives, but the momentum generated by the launch must not be allowed to disappear.
Chilekezi expects the sector to record more than 35 per cent growth in premium income, arguing that stronger operators, improved claims administration and greater public participation could change the industry’s growth story.
He also believes technology must become a major driver of the programme.
Digital platforms and insurtech, he said, should not be targeted only at young people or underserved communities but should become part of the way insurance is delivered to the entire Nigerian market.
For Chilekezi, the industry also needs more innovative products that respond to the actual needs of Nigerians.
That is where the real test of the ISSP begins.
Nigeria does not merely need more insurance policies. It needs insurance products that people understand, can afford and can easily access.
A trader should be able to insure his business without complicated procedures. A farmer should be able to protect his crops. A young worker should be able to buy affordable life insurance digitally. Small businesses should have access to protection against fire, theft, accidents and other risks that could wipe out years of investment.
But insurance experts say getting Nigerians to buy policies will depend largely on one thing: trust.
Insurance enthusiast and advocate, Mr. Ade Adesokan, warned that the launch of the ISSP should not become another government programme that generates headlines but produces little measurable change.
He called on NAICOM to establish a public ISSP performance dashboard showing progress under each of the six pillars.
Every pillar, he said, should have clear targets and measurable indicators published regularly.
If NAICOM says it wants to improve insurance literacy, Nigerians should be able to see how many people have been reached. If thousands of insurance professionals are to be trained, the public should know how many have actually completed the training. The same should apply to MSMEs covered, women reached and young Nigerians brought into the insurance market.
Adesokan also wants NAICOM to set 90-day, 180-day and 12-month milestones for each pillar, with clearly identified officials or institutions responsible for delivering them.
His argument is straightforward: Nigerians have heard many promises before. What they now want is evidence.
He also called for an independent monitoring and evaluation system, a claims settlement compliance index, stronger state-level insurance activation and proper tracking of digital insurance penetration.
For insurance companies, he wants the ISSP to become more than a regulatory programme.
Operators, he said, should embrace better underwriting, develop new products, improve distribution, jointly support public education and make consumer protection a board-level responsibility.
This is particularly important because recapitalisation has raised expectations.
With more capital in the system, Nigerians will reasonably expect insurers to have greater capacity to underwrite major risks and settle genuine claims.
The Head, Commercial Division of Leadway Assurance, Mr. Olawale Alao, sees the ISSP as a timely response to both the structural and perception problems facing the industry.
He believes the programme can help change the way Nigerians view insurance — from an optional financial product to an essential part of everyday financial planning.
For Leadway, supporting the ISSP through sponsorship of its launch reflects the company’s commitment to strengthening awareness, building confidence and making insurance more accessible.
The focus on young Nigerians is particularly important.
Nigeria has a huge youthful population, yet young people remain underrepresented among insurance customers. If the industry fails to win this group now, it risks losing a generation of potential policyholders.
The same applies to women and MSMEs.
Women play a major role in Nigeria’s trading and business ecosystem, while MSMEs account for a significant portion of economic activity and employment. Yet many operate without adequate insurance protection.
Bukola Ifemade, Team Lead of the ISSP Design Team and Managing Director of EMDI Capacity Development Ltd., believes the sector has enormous potential if stakeholders work together.
He said the programme’s launch should be seen as the beginning of mobilisation, requiring strong partnerships and sustained commitment to innovation and inclusion.
But while the regulator is setting ambitious targets, the most important issue remains claims.
For the average Nigerian, the success of an insurance company is not measured by the size of its office, number of branches or amount of capital raised.
It is measured by what happens when disaster strikes.
If a policyholder suffers a loss and the claim is genuine, how quickly does the insurer respond?
This is why Omosehin has repeatedly placed prompt claims settlement, professionalism, strong governance, solvency, transparency and consumer protection at the centre of the industry’s next phase.
His message is that innovation and expansion cannot come at the expense of policyholders.
NAICOM is expected to continue creating room for innovation and digital transformation, but operators must meet prudential standards and maintain ethical business practices.
The Nigeria Insurance Industry Reform Act 2025 provides the legal foundation for the new direction. The recapitalisation has provided stronger financial muscle.
The ISSP is now expected to provide the strategy. What remains is execution.
The industry must demonstrate that recapitalisation was not simply about forcing companies to raise more money or reducing the number of operators.
The bigger objective is to build an industry capable of carrying bigger risks, serving more Nigerians and contributing more meaningfully to the economy.
The new capital should translate into better technology, stronger underwriting, improved customer service, innovative products and faster claims settlement.
For NAICOM, the challenge is equally enormous.
The regulator must balance growth with discipline, innovation with consumer protection and expansion with financial stability.
Omosehin believes the future of insurance is a shared responsibility.
The regulator will provide policy direction and oversight; insurers must create products and expand distribution; professional bodies must raise standards; development partners can provide technical support; educational institutions must develop talent; and the media must help Nigerians understand insurance.
That collective effort will determine whether the ISSP becomes another ambitious policy document or the turning point the industry desperately needs.
Nigeria has completed the difficult task of recapitalising its insurance companies.
The next challenge may be even harder which is winning the confidence of the millions of Nigerians who have remained outside the insurance net.
If NAICOM and operators can make insurance simpler, more affordable, more accessible and, most importantly, more reliable when claims are made, the industry’s trillion-naira capital base could become a powerful foundation for growth.
But if Nigerians continue to struggle with complicated products, poor distribution and delayed claims, bigger capital alone will not change the industry’s fortunes.