 Follow Us on Google

Banks and other financial institutions have been urged to adopt real-time cash-flow data and analytics to identify early signs of financial distress among small and medium-sized enterprises (SMEs), rather than waiting for borrowers to default.
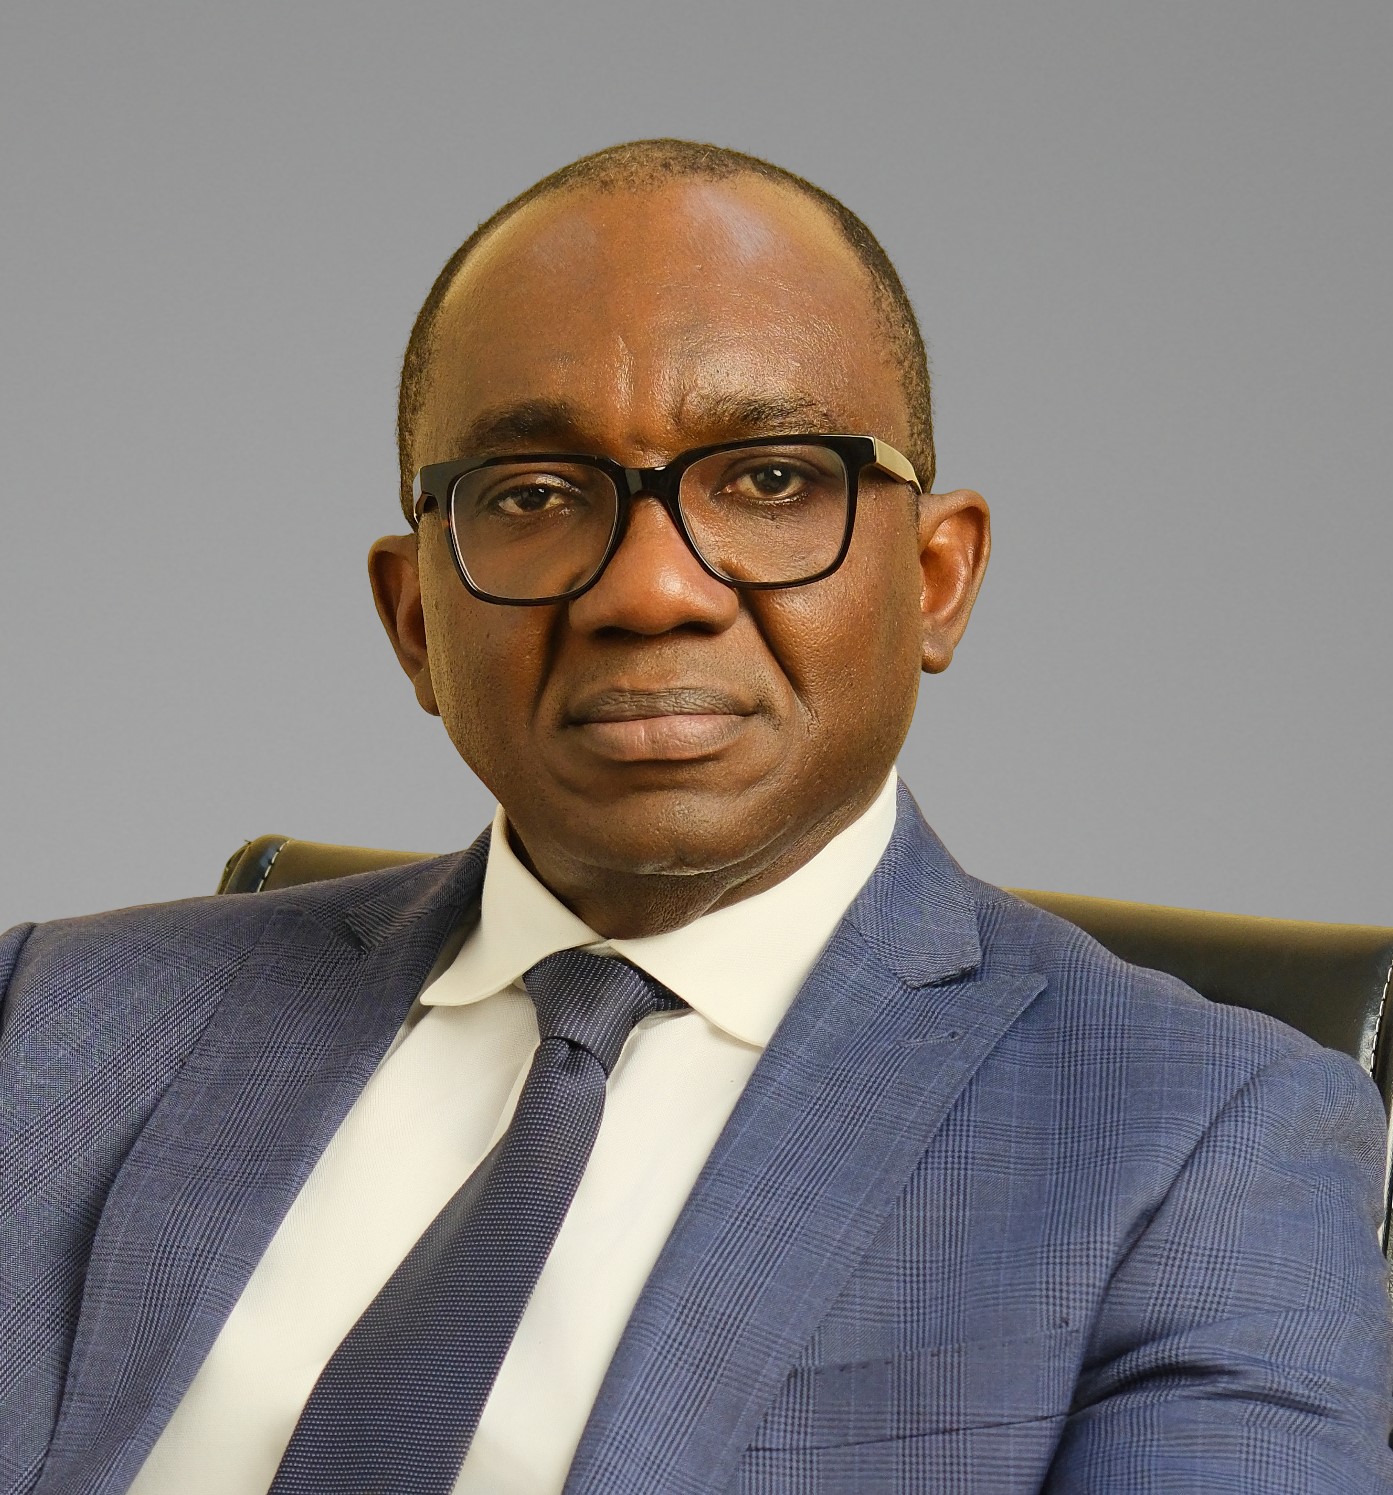
Winston Osuchukwu, Founder and Chief Executive Officer of Mathesis Analytics Inc., made the call while highlighting the limitations of traditional credit assessment systems in detecting changes in the financial health of SME borrowers.
According to him, a missed loan payment is rarely the first indication that a business is experiencing financial difficulties, with warning signs often emerging weeks or months before an actual default.
Osuchukwu said many traditional credit systems were designed primarily around fixed information collected during loan origination and periodic reviews.
He noted that such systems could struggle to analyse continuous transaction data and identify subtle changes in a borrower’s day-to-day cash-flow behaviour.
He identified four key signals lenders should monitor more closely: slower vendor payment velocity, the illusion of liquidity, rising outflow concentration and a deteriorating cash buffer before repayment.
On vendor payments, Osuchukwu said persistent delays could indicate growing pressure on a company’s working capital, even when the business continues to meet its loan obligations.
He explained that while an isolated delay may have little significance, a pattern of increasingly late payments could provide an early indication of financial stress.
He also cautioned lenders against relying solely on the balance of a borrower’s account when assessing repayment capacity.
According to him, an SME experiencing financial pressure could temporarily boost its balance by borrowing from another lender or delaying payments to creditors before a scheduled loan repayment.
He added that lenders could lose visibility into a business’s overall financial position when an SME distributes its transactions and deposits across several banks.
“Without a consolidated, real-time view of both when and where money is moving, lenders face a dual risk: penalising a healthy business because they cannot see the full picture, or missing genuine liquidity signals because one account looks fine in isolation,” he said.
Osuchukwu further identified changes in spending patterns as another potential warning signal.
He said a sudden increase in payments to a smaller group of vendors, greater reliance on short-term financing or increased transfers from a primary business account could indicate tightening working capital.
However, he stressed that such patterns should be assessed against the borrower’s normal business cycle rather than automatically classified as distress.
Other News
He cited seasonal businesses as an example, noting that some companies naturally experience periods of concentrated spending because of the nature of their operations.
A hibiscus aggregator, for instance, may significantly increase payments to farmers during a short harvest period without this necessarily indicating financial difficulty, he explained.
The critical issue, he said, is determining whether current cash-flow behaviour represents a significant departure from the company’s historical pattern.
Osuchukwu also pointed to a declining cash buffer as an important indicator of potential credit risk.
He said an SME could continue making its loan repayments on time while its available operating cash steadily declines.
Traditional systems may confirm that sufficient funds were available on the day a repayment was made but fail to capture deterioration in liquidity between repayment dates, he noted.
He argued that the significance of these indicators becomes clearer when multiple signals are analysed together.
An isolated unusual transaction or delayed payment may have several explanations, but a combination of weakening inflows, delayed payments and a shrinking cash buffer could point to a broader deterioration in liquidity.
Osuchukwu said financial institutions could use transactional data to establish a behavioural baseline for individual SME borrowers and identify significant deviations from their normal financial patterns.
Such real-time visibility, he added, could give lenders an opportunity to intervene before a loan becomes seriously delinquent.
Rather than waiting for missed payments, lenders could consider measures such as restructuring a facility, extending its tenure or engaging the borrower when early warning signs emerge.
“The goal is not to replace established credit infrastructure. Nor is it to trigger false alarms over temporary disruptions. It is to make existing systems more responsive,” Osuchukwu said.
He said converting detailed cash-flow information into actionable credit intelligence could help financial institutions manage their loan portfolios while potentially improving access to credit for viable SMEs that may not fit conventional underwriting models.
For Nigeria’s financial sector, the increasing use of transaction data and digital analytics could therefore provide lenders with an additional layer of information for assessing SME creditworthiness and managing emerging risks.