 Follow Us on Google

…‘The rails exist, but the rules don’t connect’
…Africa’s cross-border payments could hit $1trn by 2035
By Chinenye Anuforo from Nairobi, Kenya
Africa’s digital payment systems are already capable of moving money across borders, but fragmented regulations are preventing them from working seamlessly, the African Union Commission (AUC) has said.
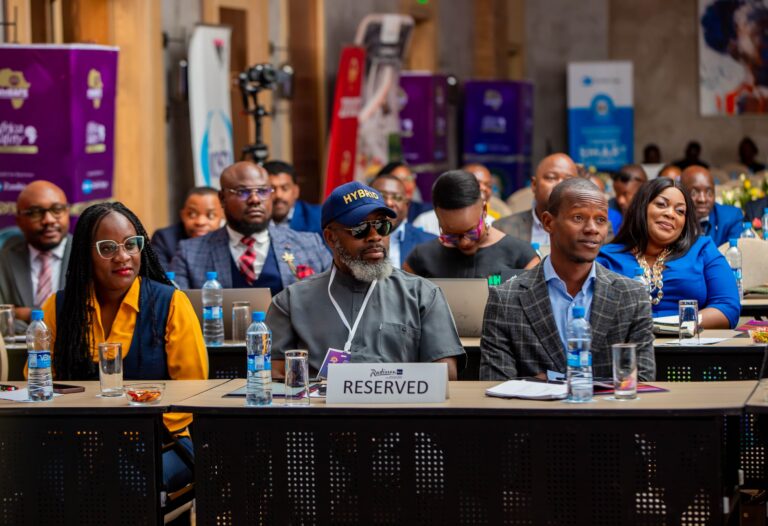
Dr. Patrick Olomo of the African Union Commission, speaking at the AfricaNenda Media Training in Nairobi, Kenya, said the continent’s biggest challenge was no longer the absence of payment infrastructure, but the inability of regulatory systems to work across national borders.
“The rails exist. The payment fails at the border because the rules do not travel with it,” Olomo said.
His comments came as Africa pushes for a continent-wide regulatory harmonisation framework that could require an estimated $120 million implementation fund and a binding African Union legal instrument to enable seamless cross-border digital payments.
The proposed framework, developed through collaboration between the AUC and AfricaNenda Foundation, is aimed at addressing regulatory fragmentation across African countries, which experts say remains one of the biggest barriers to deeper digital payment integration.
Presenting the framework, Jacqueline Jumah, Director, Advocacy and Capacity Development, AfricaNenda Foundation, said a feasibility study had established that the proposed framework was legally, technically, economically and from a governance standpoint feasible, but only if critical conditions were met.
According to her, legal feasibility depends on the adoption of a binding AU instrument, while effective governance would require an AACB mandate with enforcement power. Technically, ISO 20022 and the interlinking of instant payment systems were identified as key levers.
Jumah said three major gates must be opened before the framework can move from consensus to implementation.
These are the adoption of a binding AU legal instrument; the establishment of an AACB-anchored supervisory authority with a funded secretariat and binding standards; and securing a $120 million implementation fund through commitments from multilateral development banks, member states and philanthropic organisations.
The proposed legal instrument is expected to provide the continental foundation for regulatory convergence rather than create another payment system.
The urgency of the initiative is underscored by the rapid growth of Africa’s cross-border payments market.
According to the presentation, Africa’s cross-border payments were worth $329 billion in 2025 and could approach $1 trillion by 2035.
Yet, despite the growth in payment activity, Africans continue to pay heavily to move money across borders.
The average cost of sending remittances to sub-Saharan Africa stands at 7.9 per cent, more than twice the Sustainable Development Goal target of three per cent.
At the current rate, sending $200 to sub-Saharan Africa costs about $15.80, compared with $6 if the cost falls to the three per cent target.
That means about $9.80 is lost on every $200 transfer, even before foreign-exchange spreads, delays and informal-channel risks are considered.
The proposed framework also highlighted the cost of currency fragmentation, estimating that about $5 billion is lost annually through currency conversion when transactions are routed through the US dollar and euro.
The presentation estimates that as much as $1 billion a year could be recovered if fees were reduced to three per cent on 100 million transfers, with annual benefits potentially exceeding the 10-year implementation cost as early as the first year.
The regulatory harmonisation framework identifies eight areas where African countries need greater convergence.
These include licensing and passporting, interoperability standards, anti-money laundering and counter-terrorism financing, customer due diligence, consumer protection, data governance, supervisory architecture, settlement and liquidity, as well as a binding AU instrument.
For fintech companies and other payment service providers, the proposed risk-tiered passporting model could make it easier to expand into participating African markets by reducing some of the regulatory barriers associated with operating across multiple jurisdictions.
Jumah also identified Nigeria and Ghana as a potential pathfinder corridor, pointing to the interconnection of their national payment switches and Nigeria’s relatively mature instant-payment ecosystem.
The proposed implementation would take place over 10 years.
The first phase, covering Years One to Three, will focus on adopting the AU protocol, establishing the AACB steering structure, publishing an open API standard and securing the implementation fund.
The second phase, covering Years Four to Six, will focus on continent-wide ISO 20022 adoption, a continental electronic KYC register, regulatory sandboxes and tiered KYC mutual recognition.
The final phase, covering Years Seven to 10, will seek full interlinking of instant payment systems, establish dispute-resolution mechanisms and expand participation to countries that ratify the framework.
However, the framework does not envisage a one-size-fits-all approach across Africa.
Instead, countries and regional blocs would be grouped according to readiness, with pathfinders expected to commit early, pilot the framework and demonstrate that cross-border regulatory convergence can work in practice.
The presentation identified WAEMU, EAC, ECOWAS, CEMAC and SADC as pathfinders; COMESA as a fast follower; and AMU, CEN-SAD and ECCAS, excluding CEMAC, as capacity builders requiring additional technical assistance.
Jumah said the approach was necessary because African countries are at different stages of payment-system development and regulatory preparedness.
The framework’s three-year development process involved consultations with central banks, regional economic communities, banks, mobile money operators, fintech companies, data protection authorities and consumer groups.
More than 150 private-sector participants took part in forums in Kigali, Johannesburg, Abidjan and Lagos, while the process secured formal endorsements and decisions from AU specialised technical committees and the AACB Assembly.
The initiative has also shifted towards greater ownership by African central banks.
According to the presentation, AACB Decision No. 21 placed leadership of the Payment Systems Integration Task Force within the Association of African Central Banks, with AfricaNenda supporting the process.
The initiative was subsequently renamed from the proposed PSDA framework to “Harmonization of Regulation to Enable Cross-Border Payments in Africa” to make clear that it is a coordination mechanism rather than a directive.
However, stakeholders acknowledged that agreement on common rules would not automatically translate into implementation.
Key questions remain around how much regulatory sovereignty countries will be willing to pool, how common rules will work across 42 currencies and different exchange-control regimes, which regulatory area should come first, and whether mutual recognition can work without full harmonisation of data and AML/CFT rules.
The framework also raises a critical funding and ownership question: who will provide the $120 million implementation fund and who will carry the work beyond October 2026?
For Africa, the stakes go beyond cheaper transfers.
Greater regulatory convergence could strengthen intra-African trade, support digital financial services and make it easier for businesses and fintechs to operate across borders.
The framework also links regulatory harmonisation to the wider digital trade agenda, with the initiative noting that the success of the AfCFTA Digital Trade Protocol will depend partly on the quality and alignment of national rules.
For now, the challenge is no longer simply building payment rails.
It is creating common rules that allow those rails to work across Africa’s borders.