 Follow Us on Google

•MPC wants revenue reforms accelerated
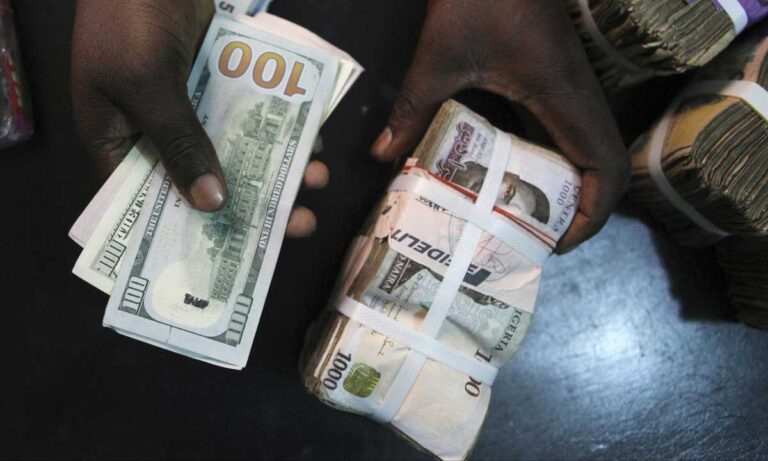
Despite collecting about N5.08 trillion in revenue for the first quarter (Q1), the federal government missed its prorated target of N9.22 trillion by 44.93 per cent as higher global crude prices failed to compensate for lower oil production and weak remittance performance.
The shortfall which was disclosed in the Federal Government’s Q1 2026 Budget Implementation Report, underscores a persistent weakness in Nigeria’s public finances that even when oil markets move in the country’s favour, the benefits are not fully converted into budgeted revenue. Crude oil had averaged $83 per barrel during the quarter under review, 27.99 per cent above the $64.85 benchmark in the 2026 budget, yet production averaged 1.55 million barrels per day, 15.76 per cent below the 1.84 million barrels per day assumption.
The production gap proved decisive as gross oil revenue stood at N2.97 trillion against a prorated target of N9.33 trillion, leaving a shortfall of N6.36 trillion, or 68.20 per cent. The report linked the underperformance to crude oil theft, pipeline vandalism, security challenges, underinvestment in technology and infrastructure, corruption and regulatory uncertainty.
Furthermore, the weakness cut across major oil revenue lines. Crude oil and gas sales generated N180.05 billion, 69.23 per cent below the quarterly estimate of N585.22 billion. Petroleum profit and gas taxes brought in N1.34 trillion, missing the N5.98 trillion target by 77.52 per cent, while royalties amounted to N1.53 trillion, 43.51 per cent below projection.
The report observed that stronger GDP growth, higher international oil prices and improved external indicators had not yet translated into commensurate revenue performance, a conclusion that places renewed attention on production security, metering, infrastructure and the efficiency of revenue collection and remittance. Non-oil revenue provided some support but could not close the gap. Gross non-oil receipts reached N4.91 trillion, compared with a quarterly target of N7.26 trillion, leaving a shortfall of N2.35 trillion, or 32.34 per cent. Value Added Tax and Company Income Tax grew 17.06 per cent and 23.68 per cent year-on-year respectively, but Customs revenue declined by 9.23 per cent compared with the same period in 2025.
These figures suggest that while tax reforms are beginning to support collections, non-oil revenue remains insufficient to absorb shocks in the oil sector. For a budget that depends heavily on stronger domestic revenue mobilisation to reduce borrowing, the Q1 outcome raises concerns about the durability of Nigeria’s fiscal improvement.
Experts have warned that the country’s mounting debt burden is increasingly threatening to undermine its development ambitions.
They added that the growing concern is not necessarily that Nigeria is on the brink of sovereign default, but that the rising cost of existing obligations could progressively restrict the government’s ability to finance development, respond to economic shocks and meet the expectations of its citizens. Already, the FG spent N4.63 trillion servicing debt in the first quarter, exceeding its prorated target of N3.88 trillion by 19.27 per cent. That amount was only N0.45 trillion below the total revenue collected in the quarter, effectively leaving limited room for capital investment and social spending.
The report warned that the elevated debt-service burden continues to constrain resources available for capital investment and social and economic programmes.
It said the government recorded a fiscal deficit of N4.69 trillion in the quarter, financed largely through domestic borrowing, alongside project-tied multilateral and bilateral loans and privatisation proceeds.
The strain is already visible in budget execution. Releases for the 2026 capital budgets of ministries, departments and agencies had not commenced by March 31, as the utilisation period for 2025 capital releases was extended to December 31, 2026. The delay means planned infrastructure and public investment projects face additional timing risks at a moment when revenue is already under pressure.
Commenting, Monetary Policy Committee member, Aloysius Uche Ordu in his personal statement maintained that fiscal discipline remains essential as Nigeria moves toward its inflation target.
Ordu noted that gross federation revenue rose from N3.772 trillion in June to N5.524 trillion in August, reflecting early gains from the Nigeria Tax Acts 2025, higher domestic crude production and favourable oil prices.
He however warned that debt service remains a heavy burden, absorbing more than half of current government revenue and limiting room for productive spending.
Citing the Debt Management Office (DMO) data, he said N2.14 trillion and $870.7 million went to domestic and external debt service respectively in Q2 2026, while public debt stood at N166.79 trillion, or 36 per cent of GDP, at end-June.
Calling for a faster revenue reform through full implementation of Executive Order 9, 2026, Ordu said, “Revenue reform needs to move faster, through full implementation of Executive Order 9, 2026, and through stronger tax effort and sound public financial management.
Timely publication of budget information matters for good policymaking, and it will matter even more as Nigeria moves to an inflation-targeting framework”.
The Q1 figures make clear that higher oil prices alone cannot secure Nigeria’s fiscal position. Without a sustained recovery in crude output, stronger remittance discipline and faster growth in non-oil collections, the government will continue to face difficult choices between borrowing, delaying capital projects and narrowing the space for essential public spending.