 Follow Us on Google

By Chinwendu Obienyi
On October 1, 1960, Nigeria gained independence with an economy built largely around agriculture and commodity exports.
Cocoa, groundnuts, palm produce and other primary products generated more than three-quarters of the country’s foreign exchange at the time. Gross domestic product was estimated at about $4.2 billion while per-capita income stood near $93.
Nonetheless, any account of Nigeria’s 66-year post-independence journey would be incomplete without a prominent mention of the banking and finance industry.
The sector tells a story of humble beginnings, from a small, largely foreign-dominated banking system to today’s highly regulated, consolidated and increasingly digital financial sector.
The industry has, indeed, undergone repeated cycles of regulation, liberalisation, crisis, consolidation and technological change since independence in 1960.
A Central Bank of Nigeria (CBN) historical review identifies independence, the establishment of the apex bank, the civil war, the oil boom and its collapse and changing government policies as major forces that have shaped the nation’s financial system.
The CBN was established in 1958 and commenced operations in 1959.
The Banking Act of 1969 subsequently strengthened regulation, covering issues including bank licensing, capital requirements and supervision.
The sector changed dramatically in 1986, when the Structural Adjustment Programme liberalised banking and encouraged new entrants.
The rapid expansion was followed by widespread distress. In 1988, the Nigeria Deposit Insurance Corporation (NDIC) was established to protect depositors and promote confidence in the banking system.
By 1994, the Failed Banks (Recovery of Debts) and Financial Malpractices Act introduced tougher measures against distressed banks. The period also witnessed the liquidation of several troubled institutions.
A major turning point came in 2004–2005, when the CBN, under Prof Charles Soludo, raised the minimum capital for commercial banks from N2 billion to N25 billion.
Banks were forced to merge or acquire one another, reducing the number of banks and creating larger institutions. Ultimately, the number of banks shrunk from 89 to 25.
The 2009 banking crisis, triggered partly by weaknesses exposed during the global financial crisis, brought another round of reforms focused on corporate governance, risk management and financial stability. It also led to the creation of the Assets Management Company of Nigeria (AMCON).
The following decade saw rapid growth in electronic banking, mobile money, ATMs, cards, internet banking and instant payments, fundamentally changing how Nigerians conduct transactions.
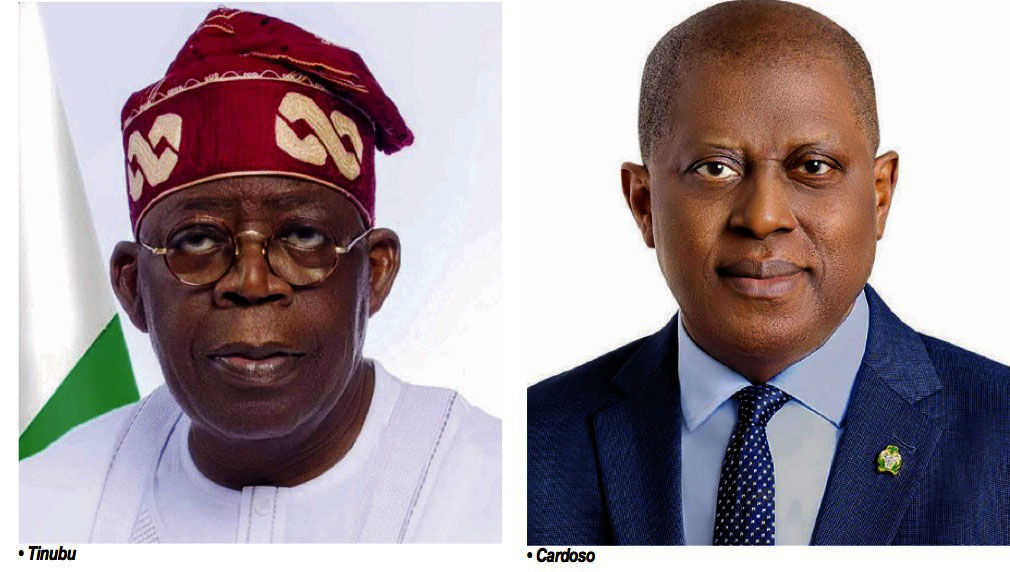
From 2023, the CBN under Olayemi Cardoso, began another reform phase, including stronger supervision and efforts to strengthen banks’ capital positions.
In March 2024, the CBN raised minimum capital requirements to N500 billion for banks with international authorisation, N200 billion for national banks and N50 billion for regional banks.
By 2026, the industry had entered another phase of recapitalisation, digital payments, tighter cybersecurity and fraud controls, while banks continued adapting to changing regulation and technology.
Despite these, there are growing questions like how Nigeria can convert its enormous human and material resources into broad-based prosperity.
The answer will determine whether the latest reforms become another temporary stabilisation episode or the beginning of a more durable transformation.
Economy shaped by oil
As stated earlier, Nigeria’s early post-independence years were marked by relatively strong growth. Agriculture dominated production and employment, while regional economies developed around cash crops and trade. The discovery and commercial exploitation of crude oil, however, fundamentally altered the economic structure.
Nigeria joined OPEC in 1971, and the oil boom of the 1970s brought unprecedented revenues. But it also weakened incentives to diversify production, encouraged fiscal expansion and increased the economy’s exposure to global commodity prices.
Over time, agriculture lost its dominant position, manufacturing remained constrained by infrastructure and foreign-exchange shortages, and public finances became closely tied to oil earnings.
The collapse in crude prices in the 1980s exposed these weaknesses. Nigeria adopted the Structural Adjustment Programme in 1986, introducing wide-ranging reforms, including exchange-rate liberalisation, privatisation and a reduction in state controls. The period was painful, but it marked the beginning of a longer debate about the need to build a more competitive and diversified economy.
However, the return to democratic rule in 1999 created another window for reform.
Debt management improved, public-sector restructuring began, and the banking industry entered one of its most important phases.
The 2005 consolidation exercise reduced the number of commercial banks from 89 to 25, following a sharp increase in minimum capital requirements and the objective was to create stronger institutions capable of supporting larger transactions and absorbing economic shocks.
This also helped deepen financial intermediation. Banks became more prominent in corporate finance, government borrowing, payment services and household transactions. The emergence of mobile banking, fintech and electronic payments later widened access to formal financial services, even though large gaps remain.
Banking reforms and repeated tests
Nigeria’s banking industry has faced repeated tests since independence: weak corporate governance, non-performing loans, foreign-exchange volatility, sudden changes in regulation, liquidity pressures and the effects of oil-price downturns.
The 2009 banking crisis demonstrated that increased capital alone could not guarantee stability. Poor risk management and weak oversight had allowed some institutions to expand aggressively without adequate controls. The subsequent reforms strengthened supervision, improved resolution mechanisms and reinforced the role of the Nigeria Deposit Insurance Corporation (NDIC).
Since then, the sector has since become larger, more technologically sophisticated and better integrated with the capital market. But its core challenge has remained the same: whether banks can mobilise deposits and convert them into affordable, productive credit for businesses and households.
The latest recapitalisation exercise represents another major turning point. According to the CBN, 33 banks met the March 31, 2026 deadline and raised a combined N4.65 trillion in new capital. About 72.55 per cent of the funds came from domestic sources, while 27.45 per cent was sourced internationally.
The exercise has strengthened capital buffers and improved the sector’s capacity to absorb shocks. It should also enable banks to finance larger projects, support cross-border transactions and compete more effectively in a changing financial-services environment.
However, recapitalisation is not an end in itself. Stronger balance sheets will only produce wider economic benefits if they result in better credit allocation, improved risk management and greater lending to productive sectors.
As analysts at Meristem Research noted, banks are expected to deploy the new capital toward expanding loans, investing in technology and supporting the real sector. The challenge is to ensure that this lending is not concentrated only in government securities, large corporations and low-risk transactions.
The reform reset
Nigeria’s current economic phase began with a series of difficult reforms, including the removal of the petrol subsidy and the unification of foreign-exchange markets. These measures were intended to correct long-standing distortions, improve fiscal sustainability and restore confidence in the naira.
The immediate consequences were severe. Transport and food costs rose, businesses faced higher operating expenses, and households experienced a sharp decline in real purchasing power. Inflation reached very high levels, while the depreciation of the naira increased the local-currency cost of imports and foreign obligations.
But the reforms have also produced signs of stabilisation. The World Bank said inflation declined from 33.2 per cent in 2024 to 23 per cent in 2025, supported by tighter monetary conditions, lower exchange-rate volatility and improved agricultural output. It also said economic growth held at about 4 per cent in 2025, driven largely by services, particularly information and communications technology, finance and real estate. The International Monetary Fund (IMF) projects growth of 4.1 per cent in 2026 and 4.3 per cent in 2027. It expects services, agriculture, real estate, information and communications, and oil and gas to remain key drivers. However, the Fund also projects inflation at 17 per cent by the end of 2026, reflecting higher food and transport costs.
These projections indicate a recovery, but not yet a transformation. Growth of about 4 per cent may be positive in statistical terms, yet it remains insufficient for a country with a rapidly expanding population, high unemployment and significant infrastructure deficits.
The World Bank has warned that poverty reduction will require faster and more broad-based growth. Its latest projections put average growth at about 4.2 per cent between 2026 and 2028, but the bank says inflation remains a major threat to household welfare.
New monetary-policy direction
The Central Bank of Nigeria’s decision in September to reduce the Monetary Policy Rate from 26.5 per cent to 23 per cent marked a significant policy shift. The 350-basis-point cut suggests that the Monetary Policy Committee believes inflation and exchange-rate conditions have improved sufficiently to allow some support for growth.
Economists have described the move as a potential relief for businesses, households and government finances. Lower interest rates could reduce borrowing costs, encourage investment and improve the ability of firms to finance working capital.
Chief Executive Officer, Centre for the Promotion of Private Enterprise, Muda Yusuf, described the rate reduction as timely, while Professor Uche Uwaleke, president of the Capital Market Academics of Nigeria, linked the decision to moderating inflation, improved foreign-exchange liquidity and greater exchange-rate stability.
The impact on banks, however, will be mixed. Lower rates could stimulate loan growth, but they may also reduce yields on financial assets and place pressure on net interest margins if lending rates decline faster than deposit costs. The outcome will depend on the speed of balance-sheet repricing, the strength of credit demand and the quality of risk management.
The CBN retained the cash reserve requirement for deposit money banks at 45 per cent, signalling that it still considers liquidity management and financial stability important. Analysts say the combination of stronger bank capital and lower policy rates could create room for carefully priced lending to the real economy.
Hence, the danger is that banks may continue to prefer government securities and other low-risk assets if private-sector lending remains difficult or risky. In an economy where public borrowing needs are large and yields have historically been attractive, government debt can crowd out private credit.
This is why the next phase of banking reform must go beyond capital adequacy. It must address credit infrastructure, collateral enforcement, credit information, sector-specific risk and the high cost of doing business.
What lies ahead
Experts who spoke to Daily Sun, noted that Nigeria’s economic future will depend on some priorities.
Chief Economist and Partner, SPM Professional, Paul Alaje, said the country must firstly consolidate macroeconomic stability, adding that exchange-rate reforms need to be supported by adequate foreign-exchange liquidity, transparent market rules and stronger confidence in the naira.
“A stable currency would reduce inflationary pressure and improve planning for businesses. Also, fiscal reform must become more credible. Nigeria’s revenue base remains too narrow, while debt-service obligations continue to constrain public spending. Borrowing should increasingly support infrastructure and productive investment rather than recurrent expenditure.
The economy must grow faster than the population and create more jobs. Services such as technology, finance, logistics, entertainment and telecommunications have shown strong potential, but agriculture and manufacturing must also become more productive and competitive”, Alaje said.
Echoing the same sentiment, President, Chartered Institute of Bankers of Nigeria (CIBN), Dr Dele Alabi, reiterated that
banks must turn recapitalisation into a lending opportunity.
According to him, stronger capital should support small and medium-sized businesses, exporters, manufacturers, farmers and infrastructure developers.
“The World Bank has previously highlighted the limited access of smaller firms to formal credit, despite their importance to employment and growth”, Alabi said.
He noted that although MSMEs remain constrained by operating costs, limited access to market, poor governance, low productivity, slow digital adoption, these can be tackled by the government via the provision of shared infrastructure, business advisory services, capacity building, tech support, market linkages and easier access to finance (provided by banks).
“In this way, the gains of recent reforms can transform third aggregate indicators to stronger businesses, better jobs, higher incomes and more resilient communities.
Hence, reforms must improve living standards, not only economic indicators. A fall in inflation is important, but Nigerians also need higher real wages, reliable electricity, better transport, affordable housing and improved access to health and education”, Alabi stressed.
He added that the country’s banking industry can play a central role in this process. “Banks are not merely financial intermediaries; they are transmission channels for monetary policy, investment and economic opportunity. If they lend more efficiently and manage risks better, they can help convert capital into factories, farms, homes, businesses and jobs”, the CIBN President stated.
Conclusion
At 66, Nigeria has moved through an extraordinary economic journey, from an agriculture-led colonial economy to an oil-dependent federation, from financial instability to repeated banking reforms, and from cash-based transactions to one of Africa’s most dynamic digital-payment markets.
Although, the progress is real, it remains incomplete. The economy is more diversified than it was at independence, yet oil still matters greatly. The banking sector is stronger, yet credit remains expensive and unevenly distributed.
Inflation is easing, yet living costs remain high. Growth has recovered, yet poverty and unemployment continue to challenge the promise of national development.
The next chapter will, therefore, be less about announcing reforms and more about delivering results.
Nigeria’s 66th year begins with improved macroeconomic foundations, stronger banks and a cautiously more supportive monetary environment. Whether these gains become durable prosperity will depend on policy consistency, institutional discipline and the ability to make the financial system work for the productive economy.
The country has spent decades searching for stability. Its next task is to make stability meaningful to households, businesses and investors.