 Follow Us on Google

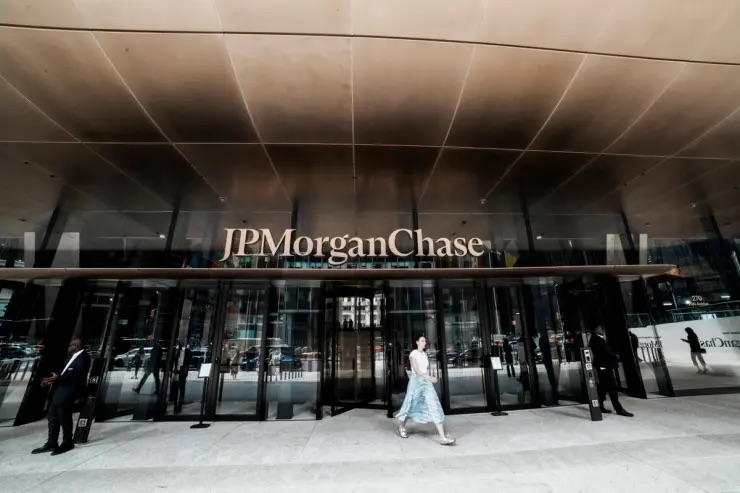
Domestic banks in Nigeria are set for tougher competition in attracting foreign capital as global financial giant, JPMorgan, prepares to enter the merchant banking market.
The banking behemoth’s anticipated debut is raising the stakes in the battle for international investors.
The development, analysts note, could reshape competition for foreign funds, with local lenders facing pressure to strengthen their market position, improve investor confidence and deepen their links with global financial markets.
A merchant bank is a financial institution that helps businesses, large companies and governments raise money, manage major financial transactions and secure funding for expansion.
Unlike ordinary commercial banks, which focus heavily on everyday banking services for individuals and businesses, merchant banks specialise in corporate finance and investment-related services.
The Central Bank of Nigeria, at the weekend, revealed that it has granted approval-in-principle for JPMorgan to realise its merchant bank ambition in the country.
This is expected to introduce a new dimension to competition in Nigeria’s financial services industry, particularly in the battle to attract international capital and finance large corporate transactions.
The bank is expected to focus on wholesale banking, capital markets and financial advisory services, although it must satisfy outstanding regulatory requirements and obtain a final licence before commencing operations.
For domestic banks, the development raises important strategic questions about their ability to retain major corporate clients, attract foreign investors and compete for high-value transactions in an increasingly interconnected financial market.
More importantly, JPMorgan’s proposed entry comes at a time when Nigeria is seeking to attract foreign capital to support investment, infrastructure development and private-sector expansion.
Although the American financial institution’s arrival will not automatically translate into increased capital inflows, its international network and capital-markets expertise could reshape competition for the business of connecting Nigerian borrowers with global investors.
Battle for international capital
For years, Nigerian banks have played an important role in connecting domestic businesses, government institutions and investors with international financial markets.
Institutions such as Access Bank, Zenith Bank, Guaranty Trust Bank, United Bank for Africa and FirstBank have developed corporate banking franchises and international relationships that support trade, financing and capital-market activities.
However, competition for international capital is becoming increasingly important as businesses seek alternative funding sources beyond conventional bank lending.
JPMorgan’s proposed establishment of a merchant bank could intensify this competition by providing a locally regulated platform through which it can expand its wholesale banking and capital-markets activities, subject to the scope of its final authorisation.
The institution already has experience advising Nigerian entities on international financial transactions, including Eurobond issuances. A local banking presence could provide a broader platform for engaging corporate borrowers, institutional investors and other market participants.
For domestic lenders, the challenge will be to demonstrate that their knowledge of Nigeria, established customer relationships and understanding of local business conditions remain valuable advantages in attracting international investors.
The competition is therefore unlikely to revolve exclusively around the size of banks’ balance sheets. Expertise in structuring transactions, assessing risks, identifying investors and executing complex deals could become equally important.
Banks that successfully combine local market knowledge with international distribution networks may be better positioned to compete for large corporate mandates.
Recapitalisation raises the stakes
JPMorgan’s proposed entry also follows the CBN’s banking-sector recapitalisation programme, which sought to strengthen the capital base of financial institutions and improve their capacity to withstand economic shocks.
Under the programme, minimum paid-up capital requirements were increased across different banking categories, including merchant banks.
The CBN has argued that stronger capital positions would improve banks’ ability to absorb losses, support larger transactions and contribute more effectively to economic development.
The development could create a more competitive environment in which banks with sufficient capital and appropriate expertise are better equipped to pursue large financing opportunities.
Nevertheless, stronger capitalisation does not automatically guarantee greater access to foreign investors.
International investors also consider macroeconomic stability, exchange-rate risks, regulatory predictability, corporate governance and the quality of investment opportunities before committing funds.
Consequently, domestic banks must translate their stronger capital positions into competitive products, credible risk-management frameworks and services that meet the expectations of international clients.
JPMorgan’s proposed entry could reinforce this pressure, particularly in capital-intensive sectors such as energy, infrastructure, telecommunications and manufacturing.
More options for corporate clients
One of the immediate areas of potential impact is competition for large corporate customers.
Major Nigerian companies often require a combination of financing, foreign-exchange services, trade finance, debt issuance and financial advisory support. Internationally active banks can help structure transactions that connect these companies with lenders and investors across different markets.
With JPMorgan seeking to establish a merchant banking operation, eligible Nigerian businesses could eventually have another institution through which to access sophisticated financing and capital-markets services. This could strengthen their negotiating position when seeking financing or appointing advisers for major transactions.
For domestic banks, retaining such customers may require more competitive pricing, faster execution and deeper expertise in complex financial products.
However, local lenders retain significant advantages. They understand the domestic regulatory environment, maintain established relationships with Nigerian businesses and have experience assessing borrowers operating under local economic conditions.
Their extensive branch networks and broader domestic banking operations may also provide customer relationships that a wholesale-focused institution would not immediately replicate.
Consequently, the likely outcome is not necessarily the displacement of domestic banks but a more competitive contest for selected corporate and institutional clients.
The degree of disruption will depend on JPMorgan’s eventual product offering, pricing strategy and appetite for Nigerian corporate risk.
Capital markets emerge as a key battleground
Nigeria’s capital markets could become an important arena for competition between domestic institutions and the proposed JPMorgan operation.
Companies and governments seeking to finance large projects can raise funds through bonds, equity offerings and other capital-market instruments.
These transactions often require financial institutions capable of structuring securities, assessing investor demand, managing issuance processes and distributing investments to buyers.
JPMorgan’s international investor relationships could potentially strengthen the connection between Nigerian issuers and global pools of capital.
For example, a Nigerian company seeking to raise funds for an expansion project may need advisers to structure a bond issue and identify international investors willing to purchase the securities.
A bank with extensive capital-markets expertise and an international distribution network could help facilitate such transactions, subject to applicable regulations and investor appetite.
Domestic banks already participate in Nigeria’s capital markets and have relationships with local issuers and investors. They could respond by expanding their own capabilities, forming international partnerships or collaborating with global institutions on larger transactions.
Such collaboration could be particularly important where a transaction requires local execution capabilities alongside international investor access.
Ultimately, deeper capital markets could give Nigerian businesses alternatives to conventional bank loans. However, greater issuance activity would not automatically mean cheaper funding, as borrowing costs would continue to reflect interest rates, currency risks and investor perceptions of Nigeria’s economic outlook.
FX and investor confidence
The proposed bank’s establishment also has implications for Nigeria’s efforts to attract foreign investment and strengthen its financial links with international markets.
Foreign capital remains important to Nigeria’s economic development, particularly in financing productive businesses, infrastructure and export-oriented industries.
JPMorgan’s decision to pursue a local merchant banking licence could be interpreted as an indication of its interest in opportunities within Nigeria’s corporate and financial markets.
However, it would be premature to interpret the approval as evidence of a guaranteed increase in foreign investment.
A banking licence does not itself represent a capital inflow, and the proposed bank’s activities will depend on the final regulatory approval, its commercial strategy and prevailing market conditions.
If its operations eventually facilitate additional foreign investment and productive business activity, the resulting transactions could support economic growth and generate foreign-exchange earnings in some sectors.
Conversely, continued currency volatility, inflationary pressures and uncertainty about investment returns could constrain international capital flows regardless of the number of foreign banks operating in the country.
The broader implication is that financial-sector reforms must be accompanied by credible macroeconomic policies and a business environment capable of supporting sustainable investment.
Domestic banks must rethink their strategies
For Nigeria’s leading banks, JPMorgan’s proposed entry presents an opportunity to reassess how they compete for international business.
One potential response is to deepen relationships with global financial institutions rather than relying exclusively on competition.
Domestic lenders could collaborate with international banks on financing arrangements, capital-market transactions and cross-border deals that require different institutions to contribute complementary expertise.
Another response is greater investment in financial technology, risk management, corporate advisory capabilities and specialist personnel.
Banks could also strengthen their international partnerships and develop products tailored to Nigerian businesses seeking foreign investment.
The challenge will be balancing these investments against the cost of funding, regulatory requirements and the risks associated with operating in a volatile economic environment.
Smaller institutions may find it difficult to match the international reach of a major global bank. However, they could continue to compete effectively in specialised market segments or through relationships with customers underserved by larger institutions.
The strategic question for domestic banks is therefore not simply whether they can match JPMorgan’s global scale, but whether they can offer compelling services that combine local expertise with access to international capital.
Risks and regulatory considerations
The benefits of increased competition will depend partly on how the CBN supervises the proposed institution and maintains consistent regulatory standards across the banking industry.
The regulator must ensure that the new bank satisfies applicable capital, governance, operational and risk-management requirements before commencing business.
It must also maintain an environment in which domestic and foreign-owned institutions can compete under clear and consistent rules.
Another consideration is the distribution of benefits. International banks often focus on large corporations, institutional investors and substantial transactions because these activities can justify the cost of specialised financial services.
As a result, small businesses and ordinary households may not experience immediate improvements in access to credit.
The wider economic benefits will depend on whether increased capital-market activity and corporate financing translate into productive investment, business expansion and employment.
Foreign-currency borrowing also requires careful management. Companies that borrow in dollars but earn most of their revenue in naira can face substantial repayment difficulties if the local currency depreciates.
For this reason, any expansion in international lending should be accompanied by appropriate risk assessment and prudent borrowing practices.
Outlook
JPMorgan’s proposed merchant bank could mark an important development in Nigeria’s efforts to deepen its financial markets and strengthen connections with international investors.
For domestic banks, it introduces the prospect of more intense competition for corporate clients, capital-market transactions and foreign investment mandates.
For businesses, it could eventually widen the range of financing and advisory services available, particularly for companies undertaking large projects or seeking access to international capital.
For the economy, the potential benefits include stronger financial intermediation, improved access to investment and deeper participation in global markets.
Nevertheless, these outcomes remain conditional. The CBN’s approval-in-principle is an initial regulatory clearance, not a final banking licence, and the proposed institution cannot commence operations until the remaining requirements are satisfied.
Conclusion
The broader significance will therefore depend on what follows the announcement: the bank’s eventual operating model, the transactions it facilitates and the response of domestic competitors.
Ultimately, the arrival of JPMorgan could intensify the battle for foreign capital among Nigerian banks, but the institutions most likely to benefit will be those capable of converting international relationships, local expertise and financial strength into credible investment opportunities.