 Follow Us on Google

From Adanna Nnamani, Abuja
Nigeria is stepping up efforts to bring fiscal and monetary policies into closer alignment as policymakers seek to strengthen economic stability, control inflation and promote sustainable growth.
The move is also designed to reduce policy conflicts, improve coordination and create a more predictable environment for businesses and investors.
To actualise the above objective, a Memorandum of Understanding (MoU) on Fiscal-Monetary Policy Coordination was recently signed by the Federal Ministry of Finance and the Central Bank of Nigeria (CBN).
The agreement comes at a time when the country is trying to consolidate the gains from major economic reforms while dealing with the difficult consequences of those adjustments, including inflation, high financing costs, exchange-rate pressures and the need to increase economic activity.
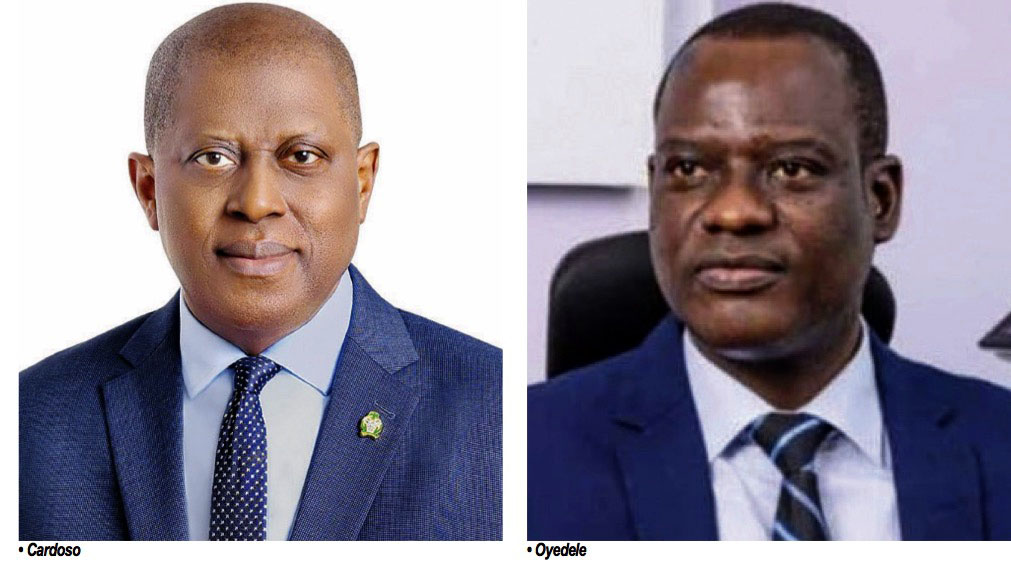
Finance Minister and Coordinating Minister of the Economy, Taiwo Oyedele, said the significance of the agreement went beyond the signing of another government document, noting that the central issue was the need to recognise that fiscal and monetary authorities may have different responsibilities but are ultimately managing the same economy.
“Good economic management requires independent institutions, but independence does not mean isolation. Fiscal and monetary authorities have distinct mandates, but we serve the same economy. Government borrowing affects liquidity and interest rates. Monetary policy affects the government’s financing costs. Tariffs and exchange rates affect prices and revenue. Spending affects demand. Agricultural policy affects food inflation.
“Our mandates are distinct; our outcomes are interconnected. That is the philosophy behind this MoU,” Oyedele said.
That relationship has become more important as the government has sought to improve revenue, manage borrowing and spending, while the CBN has been working to bring inflation under control and strengthen monetary policy transmission.
Reforms
Nigeria’s economic reforms, including the removal of petrol subsidy and changes to the foreign exchange regime, were introduced to address longstanding distortions and improve the country’s fiscal and external position. But they also brought significant adjustments for households and businesses.
The International Monetary Fund (IMF), in its June 2026 assessment of Nigeria, said reforms over the previous three years had improved macroeconomic outcomes and strengthened resilience, while noting that conditions remained difficult for many Nigerians. It said inflation had risen to 15.4 per cent year-on-year in March 2026 after more than a year of decline, partly reflecting higher international fuel and food prices.
The IMF also estimated Nigeria’s consolidated government deficit at 4.4 per cent of GDP in 2025, while oil revenues fell short of budget expectations. Government interest payments also remained a major burden.
Those figures underline the overlap between fiscal and monetary policy.
The government has to raise revenue, finance its programmes and manage its debt. The CBN, on the other hand, has to manage monetary conditions, maintain price stability and safeguard the financial system.
The decisions cannot be completely separated.
Government borrowing can influence liquidity and interest rates. Monetary tightening can affect the cost of government borrowing and private-sector financing. Exchange-rate movements affect the cost of imports, government revenue and foreign obligations. Government spending can influence demand and, depending on how it is financed, prices.
Oyedele said the MoU was intended to make the relationship between the two institutions more deliberate and less dependent on personalities.
“We are not starting from scratch. We already have the Economic Management Team, the National Economic Council, and legal linkages between the Ministry and the Bank. This MoU makes those linkages more deliberate and effective through stronger information-sharing, aligned macroeconomic assumptions, more consistent forecasts, and clearer mechanisms for resolving areas where fiscal and monetary actions may pull in different directions.
“A common understanding of inflation, growth, revenue, liquidity and the external outlook,” he said.
The distinction is important because the agreement does not mean that the Ministry of Finance and the CBN will begin doing the same job.
Rather, it is intended to ensure that each institution understands the likely consequences of its decisions on the other side of the economy.
For the government, that includes understanding how its borrowing and spending plans could affect liquidity, interest rates and inflation.
For the CBN, it means having a clearer picture of government cash positions, financing plans and fiscal developments when making monetary policy decisions.
Cardoso reacts
The CBN Governor, Olayemi Cardoso, said the relationship between the two institutions was not new and had been tested over several years.
“This occasion marks a significant milestone in our nation’s pursuit of stronger macroeconomic management, lasting economic stability and sustainable prosperity for all Nigerians. Beyond the signing of a document, it represents a shared commitment to deepen collaboration in the interest of our economy and our people.
“It is important to emphasise that this Memorandum does not create a new relationship between our institutions. The Central Bank of Nigeria and the Federal Ministry of Finance have worked together for decades in addressing critical macroeconomic issues, including inflation management, debt sustainability, budget financing, exchange rate stability, economic reform programmes and responses to domestic and global shocks,” Cardoso said.
What is changing, according to him, is that the existing cooperation is being given a more permanent structure.
“That longstanding partnership has served our country well, helping Nigeria navigate periods of both challenge and opportunity. What distinguishes today’s event is the formal institutionalisation of that collaboration.
“This Memorandum provides a structured framework for regular consultation, information exchange and policy coordination. It will strengthen collaboration in critical areas such as government cash management, debt issuance planning, liquidity forecasting, macroeconomic analysis and periodic policy consultations, thereby enhancing policy coherence and the effectiveness of economic management,” he added.
The timing also coincides with the CBN’s move towards a more explicit inflation-targeting framework.
Under such a framework, the quality of fiscal policy becomes particularly important because monetary policy cannot operate in isolation from government spending, borrowing and other economic decisions.
Cardoso said the new arrangement would help provide the fiscal environment needed for the monetary policy framework to work effectively.
“The timing of this agreement is particularly noteworthy as the Central Bank of Nigeria advances its transition towards an Inflation Targeting framework. Across the world, the success of inflation targeting is known to rest not only on the effectiveness of monetary policy, but also on the existence of a supportive fiscal environment.
“The Memorandum will also provide the foundation for developing the operational framework that will guide its implementation. Through regular dialogue, information sharing and coordinated policy assessments, both institutions will be better positioned to align their actions, minimise policy trade-offs and pursue shared national objectives,” he said.
Inflation is perhaps the clearest example of why coordination is needed.
The CBN can influence inflation through interest rates, liquidity and other monetary tools. But it cannot directly produce food, repair roads, reduce insecurity on farms or determine the cost of transporting goods across the country.
Those factors can be major contributors to price pressures.
Oyedele therefore argued that bringing inflation down must be treated as a wider government responsibility.
“Our objective is to bring inflation sustainably into single digits and keep it there , and that cannot be monetary policy’s job alone. Fiscal policy must play its part: disciplined, disinflationary spending; sound cash and liquidity management; efficient financing that does not crowd out the private sector.
“But much of Nigeria’s inflation is structural, food, imported costs, energy, logistics, which monetary policy alone cannot address,” he said.
He pointed to improved agricultural production, better seeds and yields, irrigation, climate resilience, grain reserves and improved roads linking farms to markets as part of the wider response required to tackle structural inflation.
Energy is another area where fiscal and monetary concerns meet. The removal of petrol subsidy reduced a major direct fiscal cost to the government, but also resulted in higher transport and living costs. Changes in the exchange rate added another layer of pressure because Nigeria imports a substantial range of goods and inputs.
The government has since pointed to improved foreign-exchange conditions and measures such as tax exemptions as part of efforts to moderate some of those pressures.
But the underlying challenge remains: a policy that improves one part of the economy can sometimes create pressure somewhere else.
Higher oil prices, for example, can increase government revenue and foreign-exchange inflows because Nigeria is an oil producer. At the same time, higher global energy prices can increase domestic inflation and the cost of transporting and producing goods.
The CBN Deputy Governor, Corporate Services Directorate, Dr Muhammad Abdullahi, used developments in the Middle East and possible disruptions to energy and shipping routes to illustrate how quickly one external shock can affect both sides of economic policy.
“One external shock can arrive simultaneously at the doors of fiscal and monetary policy. The fiscal authorities must assess the implications for revenue, expenditure, financing and debt.
“The monetary authorities must assess the implications for inflation, liquidity, foreign exchange, reserves and financial conditions. The Nigerian economy, however, experiences all these effects together. This is why co-ordination matters,” Abdullahi said.
The example captures one of the practical reasons for the new framework.
Nigeria could benefit from higher crude oil prices through increased export earnings, government revenue and foreign-exchange inflows. At the same time, higher energy and shipping costs could increase domestic prices, while global inflation could affect international interest rates, capital flows and financing conditions.
The two institutions may therefore approach the same development from different angles, even though the economy ultimately experiences all of its effects together.
Abdullahi said the answer was to prepare for different scenarios rather than wait until a shock had already affected the economy.
“The current oil market situation illustrates the values of such a framework. We do not know whether present disruptions will be short-lived or prolonged. Nor can we know with certainty where oil prices will be in three or six months.
“But uncertainty is not an argument for waiting, it is an argument for preparedness. Our institutions should be able to assess in advance what different oil price and production scenarios mean for fiscal revenues, for foreign exchange inflows, for reserves, for inflation, for liquidity and financing conditions,” he said.
That approach is particularly relevant to Nigeria because of the country’s continued exposure to movements in crude oil prices and production.
When oil revenue falls, government finances and foreign-exchange inflows can come under pressure. When oil prices rise, government revenue may improve, but higher global energy prices can also add to inflationary pressure.
Benefits of alignment
A coordinated assessment allows both institutions to look at the same development from their respective mandates before policy responses are made.
Government borrowing is another area where the two policies intersect.
When the government borrows heavily from the domestic market, it competes with other borrowers for available funds. Depending on liquidity and market conditions, that can influence interest rates and the amount of credit available to businesses.
The Permanent Secretary of the Federal Ministry of Finance, Raymond Omachi, said the MoU was intended to help address precisely this kind of interaction between fiscal decisions and monetary conditions.
“This ceremony is not merely about signing a document. It is a public commitment to unity of purpose. The Ministry of Finance shapes fiscal policy through spending, taxation and revenue allocation, while the Central Bank is responsible for monetary policy, price stability, currency and the financial system.
“For too long, the firewall between these functions has sometimes meant that financial system and monetary policy considerations could be addressed separately from fiscal decisions. Yet the economy does not operate in compartments. Government spending decisions can influence inflation, while monetary tightening can affect the cost of financing and economic activity,” Omachi said.
He said the agreement would help align government borrowing plans with money-market liquidity management, while also supporting the balance between inflation control and economic growth.
That balance is important because the government’s need to finance expenditure cannot be viewed separately from the private sector’s need for credit.
The objective is not simply to borrow less or to tighten monetary policy more aggressively. It is to ensure that borrowing, spending and liquidity decisions are considered together.
Another part of the framework is data.
Oyedele said better economic management depends on having timely and detailed information about what is happening across the economy.
“We cannot manage this economy well on incomplete or delayed data. As monetary policy evolves toward inflation targeting, the quality and granularity of our data matter more than ever.
“We are working with the National Bureau of Statistics to provide critical data to aid policy decisions including producer price index in addition to consumer price index, employment and productivity data, the kind of evidence that provides deeper insights on drivers of price pressure and let us see inflationary pressure before it reaches consumers,” he said.
The government is also looking at how fiscal and monetary data can be shared more efficiently. Information on government cash positions, financing plans, credit growth and foreign-exchange flows can help both institutions understand the likely consequences of their decisions.
For a government planning to borrow, knowledge of liquidity conditions and financing costs is important. For the CBN, information about government borrowing and spending plans can help in assessing their possible effect on liquidity and inflation.
That makes the sharing of information one of the less visible but potentially important parts of the MoU.
It is also part of the reason the government is emphasising institutionalisation.
Governments, Ministers and Central bank governors can change, but If regular consultations, data sharing, joint technical analysis and policy assessments become routine, future officials will inherit an established framework rather than having to rebuild coordination from the beginning.
The arrangement is also intended to preserve the CBN’s independence.
Oyedele was explicit that closer coordination should not become a mechanism through which fiscal authorities dictate monetary policy.
“The operational independence of the Central Bank remains sacrosanct. Coordination must never become fiscal dominance. The CBN will retain full independence in pursuing price and financial-system stability.
“In parallel, we are strengthening the institutions that support fiscal governance and accountability including the Fiscal Responsibility Commission, the Bureau of Public Procurement, NEITI, the Auditor-General, the National Bureau of Statistics. Strong economies are not built around strong personalities. They are built around strong institutions,” he said.
That distinction is central to the agreement.
The Ministry of Finance will continue to determine and implement fiscal policy within its mandate, while the CBN retains responsibility for monetary policy and financial-system stability.
The objective is to reduce avoidable policy conflicts, not to remove differences between the institutions.The wider objective is also to create a more predictable environment for businesses and investors.
Businesses make investment decisions based on expected costs, interest rates, exchange rates, taxes and demand. Greater policy consistency can make it easier for businesses to plan, while uncertainty can increase the cost of investment decisions.
Oyedele said the government wanted to attract longer-term investment capable of creating factories, infrastructure, technology and jobs rather than relying primarily on short-term capital.
“Capital follows trust before it follows returns. That is why policy consistency, certainty and clarity remain non-negotiable, including through the newly established Finance Bill process where legislative change is needed. We will also guard against overregulation, because several legitimate rules can still add up to an unnecessary burden on business.
“Our coordination will extend beyond conventional policy. For instance, insecurity and illicit financial flows have real economic consequences, and addressing them takes financial intelligence and economic inclusion, not kinetic measures alone,” he said.
The MoU therefore sits within a much broader attempt to make Nigeria’s economic management more predictable.
It does not remove the country’s exposure to oil-price movements, global interest rates, food and energy prices or domestic structural constraints. It also does not mean fiscal and monetary policies will always move in exactly the same direction.
What it does is create a formal framework for both sides to exchange information, discuss their assumptions and assess the consequences of policy decisions before those decisions create unnecessary pressure elsewhere in the economy.
Abdullahi said the success of the arrangement would ultimately depend on what happens after the signing.
“The agreement should therefore not be viewed as a document just to be signed. Instead, it must become a practical framework for how we work, regular consultations, appropriate information sharing, joint technical analysis, scenario planning and stress testing on matters of common interest.
“These agreements are particularly important for government cash management, liquidity forecasting, domestic finance operations and the assessment of economic conditions,” he said.
That leaves the technical teams of both institutions with much of the work ahead.
The value of the agreement will depend on the quality and timeliness of the information shared, how regularly the institutions consult and how effectively they use joint analysis to anticipate economic pressures.
For Nigeria, the stakes are broader than the relationship between two government institutions.
Inflation affects households and businesses. Interest rates affect investment and borrowing. Government borrowing affects public finances and financial markets. Exchange-rate movements affect imports, exports and prices. Oil-market developments affect revenue and foreign-exchange earnings.
All of those issues eventually meet in the same economy.
As Oyedele put it: “Nigeria has one economy. Fiscal policy cannot succeed without price stability. Monetary policy cannot deliver price stability if fiscal policy pulls in the opposite direction.
“Our task is therefore to coordinate without compromising independence, to share information without blurring accountability, and to resolve differences through evidence and in the national interest.”
The signing of the MoU has therefore formalised a principle the officials acknowledge has always existed: fiscal and monetary policy may have different institutional homes, but their consequences are felt by the same people and businesses.
The immediate task is to turn that principle into a working system.
If the framework produces regular consultations, timely data sharing, stronger technical analysis and better anticipation of economic shocks, it could make policy coordination more predictable and less dependent on the personalities occupying public offices at any particular time.
The real measure of success will be whether stronger balance sheets translate into stronger businesses and whether those businesses translate into the jobs Nigeria urgently needs.