 Follow Us on Google

Who protects Nigerians from fraud, failed transactions?
Nigeria’s digital payment revolution is making it easier to transfer money, pay for goods and services and run businesses, but billions of naira lost to electronic fraud and persistent complaints over disputed transactions are raising questions about the protection available to consumers when things go wrong.
From bank transfers that leave customers uncertain about whether their money has reached the recipient to fraudulent transactions, compromised accounts and delayed refunds, the challenges extend beyond the convenience of making payments with a mobile phone.
For many Nigerians, the problem is not simply that a transaction fails or money disappears from an account. It is what happens afterwards, the difficulty of getting a response, identifying the institution responsible for resolving the complaint, tracing the money or obtaining a refund.
Victoria Ikenna knows this frustration. She said she lost N20,000 through a digital payment transaction after attempting to purchase airtime for a customer. Although her account was debited, the recipient did not receive the airtime, and the money was not reversed.
“I lost 20K through the digital platform and never got it back. I tried sending airtime to a customer, but he never received it and the money wasn’t reversed. It was pending for weeks. I laid a complaint but nothing was done,” she said.
For Chinedu Nwabueze, the experience involved money allegedly disappearing from his account after he suspected that his ATM card details had been compromised. He said he did not pursue a formal complaint, explaining that he learnt his lesson and moved on.
Gozie Daf recounted losing N130,000 after transferring money to an individual who had promised to supply goods. According to him, the seller disappeared after receiving the payment.
Olufunke Olumuyiwa, however, had a different experience. She said a N5,000 online transaction through a platform initially failed, but her complaint eventually resulted in a refund.
Another consumer, Ogoma, said she lost N340,000 after paying into a digital payment account provided by a roadside point-of-sale operator for goods she intended to purchase. She alleged that the recipient stopped responding after receiving the money and eventually blocked her. She said she complained to the platform but was dissatisfied with the response, adding that she was advised to obtain a court order, a process she did not know how to navigate.
The cases illustrated the different problems consumers encounter in an increasingly cashless economy. While Victoria’s experience concerns a failed airtime transaction, Chinedu suspects unauthorised access to his banking details. Gozie and Ogoma describe payments to individuals who allegedly failed to deliver goods, while Olumuyiwa’s experience demonstrates that a failed transaction can be resolved through a complaint.
The incidents also highlighted why consumer protection in digital payments cannot be reduced to fraud prevention alone. It must cover the processes through which customers report problems, obtain explanations, have disputed transactions investigated and, where appropriate, recover their money.
Data from the Nigeria Inter-Bank Settlement System (NIBSS) showed that losses to digital payment fraud declined by 51 per cent to N25.85 billion in 2025, from N52.26 billion in 2024.
The number of reported fraud incidents also declined to 67,518 in 2025, from 70,111 in the previous year. NIBSS said collaborative interventions by industry stakeholders prevented about N20 billion in potential losses during the year.
Lagos accounted for 63.43 per cent of reported fraud activity, while e-commerce and internet banking were among the channels most affected. The report identified social engineering, insider abuse, SIM swap, account compromise and phishing among the methods used by fraudsters.
Presenting the figures at the 2026 Nigeria Electronic Fraud Forum, the Managing Director and Chief Executive Officer of NIBSS, Premier Oiwoh, said the industry had recorded a significant reduction in the value of losses. He, however, warned that fraud reporting remained a major concern, noting that some financial institutions had reported zero incidents.
According to him, non-reporting undermines industry monitoring and investigations because individuals involved in fraud can move from one institution to another without their activities being properly tracked. He also identified insider involvement as a major threat to the payment system.
Although the reduction in losses represents progress, it does not necessarily mean that consumers are finding it easier to recover money or resolve disputed transactions. Fraud losses, attempted fraud prevented, money traced, funds recovered and money refunded to customers are different measures. A reduction in reported losses does not establish how many victims obtained redress or how quickly their complaints were resolved.
NIBSS has established industry-wide infrastructure to support the detection and resolution of payment disputes. One of these is the Industry Dispute Resolution Solution (IDRS), which allows participating financial institutions and payment providers to raise, receive, investigate and resolve disputes arising from electronic transactions.
According to the IDRS user guide published by NIBSS, participating institutions can initiate disputes, accept or decline claims, submit further representations and, where disagreements persist, refer cases for arbitration by NIBSS. The platform also supports acquirer-initiated refunds and settlement reports that help institutions process refunds for accepted disputes.
However, IDRS is not a consumer-facing complaints portal. Customers cannot independently use it to compel another institution to return money, and its existence does not guarantee that disputed funds will be recovered. Consumers still need to know which institution is handling their complaint and what steps are being taken to resolve it.
The Central Bank of Nigeria (CBN) has established a regulatory framework intended to protect financial consumers and provide channels for resolving complaints. Its Consumer Protection Regulations 2019 require financial institutions to treat customers fairly, provide transparent information and maintain effective complaint-handling and redress mechanisms.
Under the CBN’s complaints procedure, customers are expected to first lodge complaints with their financial institution. Where the institution fails to resolve the complaint within two weeks, the customer may escalate the matter to the CBN.
The CBN also operates a Consumer Complaints Management System through which customers can track complaints lodged with their financial institutions. Its complaints portal instructs customers to obtain a complaint reference or tracking number from their bank or financial service provider before accessing the system. Institutions are expected to upload complaints to the CBN platform within 24 hours of receiving them.
The apex bank’s published complaint procedure also provides for escalation to its Consumer Protection Department where a financial institution fails to resolve a complaint within the applicable two-week period or 30 days, depending on the nature of the complaint.
The two-week period is an escalation point for unresolved complaints; it should not be confused with a universal deadline for refunding every disputed payment. Different transaction types and circumstances may attract different reversal and investigation requirements.
The CBN has also intensified its oversight of electronic payment operations. In January 2026, Deputy Governor, Financial Systems Stability, Philip Ikeazor, announced that banks had been directed to reduce fraud response times to less than 30 minutes.
The directive, announced at the Nigeria Electronic Fraud Forum technical kickoff session, was part of efforts to strengthen the industry’s response to electronic fraud. However, a requirement for faster fraud response does not automatically mean that every customer will receive a refund within 30 minutes. Responding to a fraud report, investigating a transaction and recovering money remain different processes.
In another move, the CBN and the Nigerian Communications Commission (NCC) released a draft framework 2026 to address failed airtime and data purchase transactions.
The proposed framework seeks to ensure that transactions and refunds, where necessary, are completed within 30 seconds. It also proposes automatic, real-time refunds where customers are debited without receiving the airtime or data purchased, alongside standardised error codes and improved visibility across the transaction process.
The proposal is particularly relevant to cases such as Victoria’s, where a customer is debited for an airtime purchase that is not delivered. However, the framework was released as an exposure draft and should not be presented as an already established binding rule. Its significance lies in the recognition by the regulators that failed airtime and data transactions require a more automated resolution process.
The CBN has also issued additional instant-payment security requirements through a circular dated March 12, 2026, with implementation scheduled from July 1, 2026.
The measures include options for customers to voluntarily disable instant transfers or set lower transaction limits, stronger identity verification and real-time fraud monitoring. They also provide for restrictions on the use of mobile banking applications across devices and a temporary transaction limit of up to N20,000 during the first 24 hours after activation on a new device, subject to the applicable conditions.
These measures are intended to reduce opportunities for account takeover and unauthorised access. But tighter authentication controls must be matched by accessible complaint processes and effective redress when prevention fails.
The CBN’s proposed measures to strengthen protection against authorised push payment (APP) fraud are another important development. In November 2025, the apex bank released draft guidelines for consultation that proposed clearer responsibilities for sending and receiving institutions, timelines for acknowledging and investigating complaints, and reimbursement arrangements in eligible cases.
The proposals included acknowledging complaints within 24 hours, issuing case reference numbers, completing investigations within 14 working days and reimbursing customers within 48 hours after a resolution in cases that qualify.
They also contemplated shared responsibility between institutions where neither party was negligent, while an institution found negligent could bear the full responsibility. The draft further proposed round-the-clock channels for reporting fraud and measures for withholding suspected fraudulent funds.
The proposed guidelines also set conditions for reimbursement, including prompt reporting by affected customers, cooperation with investigations and the absence of customer negligence or criminal involvement.
These were proposals for consultation and should not be mistaken for an already established universal reimbursement rule. Their significance lies in the attempt to address a persistent gap: consumers can be caught between institutions when money is transferred through the payment system and subsequently disputed.
The CBN’s Nigeria Payments System Vision 2028 also recognises the need to strengthen consumer protection as the country’s payment system develops. The document identifies gaps in the existing redress framework, including the absence of a unified dispute-resolution portal, inconsistent service timelines and limited transparency in refund processes.
Among the proposals and targets discussed in the vision are a unified redress portal, a National Financial Ombudsman Service, clearer refund timelines, consumer protection measures and public reporting of complaint-resolution performance. These are proposals and policy ambitions in the vision document, not all existing binding requirements.
The vision acknowledges that the efficiency of a payment system should not be measured only by transaction volumes, speed and technological innovation. Consumer confidence also depends on whether people can obtain timely assistance when transactions fail or money is lost.
The scale of complaints recorded by the CBN provides another indication of the pressure on the financial consumer protection system.
The CBN’s Financial Stability Report for June 2024 recorded 16,527 complaints during the reporting period, representing a 46.59 per cent increase from 11,274 complaints in the second half of 2023. Of the complaints recorded, 14,743 were reported as resolved or closed.
The report listed fraud-related complaints as the largest category, accounting for 41.49 per cent, followed by electronic and card-related complaints at 32.57 per cent and account management complaints at 22.38 per cent.
Claims associated with the complaints amounted to N12.60 billion and $1.05 million, while refunds stood at N5.47 billion and $665,126.33.
The figures demonstrate the financial implications of disputes between consumers and financial institutions. They also underline the importance of distinguishing between complaints received, complaints resolved, claims submitted and amounts eventually refunded.
The CBN’s 2022 Annual Report had similarly recorded 5,170 complaints against financial institutions, compared with 4,456 in 2021. Fraudulent transactions accounted for 1,645 complaints, while failed transactions accounted for 1,154. The report also recorded N4.88 billion in refunds during the year.
More recent figures reported from the CBN’s 2025 Annual Report indicate that financial institutions refunded N19.12 billion to customers during the year, while 18,824 complaints were resolved or closed.
The reported refund figure was higher than the N9.66 billion recorded in 2024.
The complaints data cover a broad range of banking and financial service issues and should not be interpreted as relating exclusively to digital payment fraud.
The CBN has also imposed sanctions on financial institutions over consumer complaints and regulatory breaches. Reports on the 2025 annual figures indicate that 21 financial institutions were sanctioned a total of N430 million over delayed complaint resolution and non-compliance, while 11 penalties totalling N1.26 billion were imposed in connection with regulatory breaches and failure to respond to supervisory queries.
These enforcement measures raise a further question: whether penalties are translating into improved complaint handling and better outcomes for customers.
The experience of customers dealing with payment providers also raises questions about how institutional policies work in practice.
One of the platforms, which features prominently in some of the consumer experiences in this report, has published a fraud-support section on its official website outlining procedures for reporting unauthorised transactions, securing compromised accounts and requesting assistance with disputed transfers.
Its guidance, updated in February 2026, instructs customers who notice unauthorised transactions to immediately change their passwords and contact customer support through the app or email, providing transaction details for investigation.
The company says it uses encryption, two-factor authentication and real-time transaction monitoring to strengthen the security of app transactions. It also advises customers to use strong passwords, protect their login details and promptly report suspicious activities.
However, its published guidance makes an important qualification about the recovery of funds.
According to the platform, where a customer reports a fraudulent transfer to another account, its Fraud Desk may initiate a recall request through the receiving bank. Recovery, however, depends on whether funds are still available in the beneficiary’s account, the consent of the beneficiary and the discretion of the beneficiary’s financial institution.
The company also stated that a police report or court order may be required to validate such claims. Its guidance expressly warns that fund recovery is not guaranteed.
This requirement raises an important consumer protection question, particularly for customers who may not have the resources, legal knowledge or financial capacity to obtain a court order after losing money through an alleged fraudulent transaction.
For Ogoma, who said she was advised to obtain a court order after reporting her loss, the experience illustrates the difficulty that can arise when a consumer is directed towards a legal process without adequate guidance on how to navigate it.
The distinction between a fraudulent transfer and a merchant dispute is also important. The platform’s general terms for service provide for customers to raise disputes through the bank’s in-app support channel, obtain a reference number and have certain payment disputes referred to the relevant payment gateway or merchant.
Where a dispute is resolved in the customer’s favour, the relevant payment gateway is responsible for processing the chargeback. The bank says it provides updates as it receives them from the gateway or merchant.
These terms apply to the specified payment service and should not be confused with every transfer made through its account.
Another platform also published security and customer-support procedures aimed at protecting users and helping them report suspicious activities.
Its official security guidance warns customers that the company and its agents will not request their passwords, PINs, card details or authentication tokens through unsolicited calls or emails. It advises users to report suspicious communications through the in-app customer service centre and other official support channels.
The platform provides round-the-clock customer support through its mobile application, telephone lines and WhatsApp. Its published contact information also includes channels for app, card and POS-related complaints.
The company says its in-app support system provides self-service options for transfer and card disputes, real-time information and updates on complaint resolution, as well as access to customer service representatives through live chat.
However, the existence of a 24-hour support service does not, by itself, establish how many complaints are successfully resolved, how quickly customers receive refunds or what proportion of reported fraud losses is recovered.
For Olumuyiwa, whose N5,000 failed transaction was eventually refunded, the experience shows that the complaint process can produce a positive outcome. Other consumers, however, continue to report difficulties obtaining similar resolutions.
A consumer survey by Innovations for Poverty Action (IPA), published in January 2025, provides another perspective on the challenges facing users of digital financial services in Nigeria.
The study, titled Consumer Protection in Digital Financial Services: Consumer Survey Nigeria, 2024, found that 84 per cent of respondents had experienced at least one problem with a digital financial service in the preceding year. The survey was not nationally representative, so the finding should be understood within the limits of its sample rather than as a measure of the experience of every Nigerian.
Poor network was identified by 44 per cent of respondents, while unexpected charges and fraud were each reported by 23 per cent. The study also found that 58 per cent of respondents had been targeted by a fraud attempt through a phone call or text message at some point.
Six per cent said they had lost money because of fraud or a transaction gone wrong in the preceding year. More than half of respondents did not take action to address their biggest reported problem. Among those who sought redress, 61 per cent said their issue was successfully addressed, while the reported success rate for cases involving lost or stolen funds was 56 per cent.
The findings point not only to the frequency of problems but also to the barriers that may discourage consumers from seeking redress. A customer who believes that a complaint will lead nowhere may decide to absorb the loss rather than navigate a process that appears complicated or time-consuming.
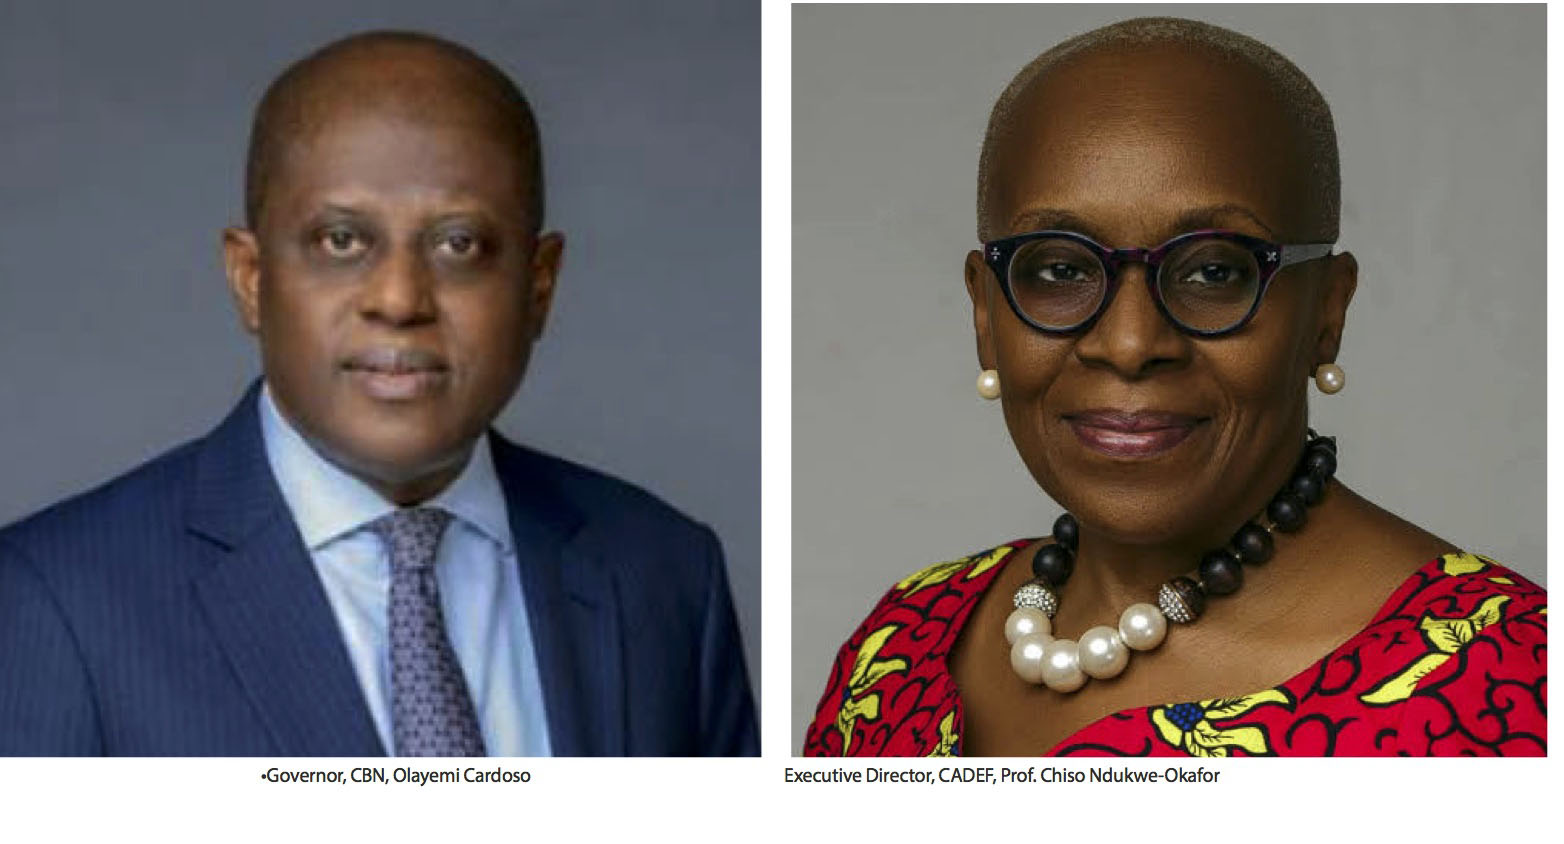
For Prof. Chiso Ndukwe-Okafor, Executive Director of the Consumer Advocacy and Empowerment Foundation (CADEF), consumer protection must go beyond the existence of complaint channels. Financial institutions must be able to investigate complaints properly, communicate clearly with customers and establish responsibility when a transaction is disputed.
Ndukwe-Okafor has cautioned against treating the use of a personal identification number or one-time password as conclusive proof that a customer knowingly authorised a transaction. While authentication records are important evidence, they should not automatically end an investigation into a disputed transaction.
A proper investigation, she argued, should examine the circumstances surrounding the transaction, including unusual login attempts, the use of new devices, SIM swaps, changes to customer information, transaction patterns and the destination account.
This is particularly important in cases involving social engineering, where a customer may be deceived into disclosing credentials or authorising a transfer without understanding the true nature of the transaction.
The consumer advocate also stressed the need for prompt acknowledgement of complaints, reference numbers, clearly identified complaint officers and a transparent process for investigation and escalation. Where fraud is reported while funds may still be available in a receiving account, the response must be sufficiently swift to allow the relevant institutions to communicate and take appropriate steps to preserve or trace the money.
Her position highlighted a weakness in a system where consumers may receive generic explanations without being told what was investigated, what evidence was considered and why a claim was accepted or rejected.
Ndukwe-Okafor has also called for greater transparency in the publication of complaint resolution times, recovered and refunded amounts, rejected claims, reopened cases and recurring causes of consumer disputes. Such information would make it easier to assess whether institutions are improving their response to complaints and whether regulatory interventions are producing measurable results.
The protection of consumers’ personal information is another part of the problem. Digital payment services depend on the collection and processing of sensitive personal and financial information, including identity details, account records, telephone numbers and transaction histories. Where such information is compromised, consumers may face risks ranging from phishing and SIM-swap attacks to account takeover and identity-related fraud.
The Nigeria Data Protection Act 2023 provides a framework for the protection of personal data and establishes the Nigeria Data Protection Commission (NDPC). Financial institutions and other organisations processing customers’ personal information are expected to comply with the law’s requirements on lawful processing, security and the protection of data subjects’ rights.
The Act also provides for notification of qualifying personal data breaches to the Commission within 72 hours of becoming aware of them. This is a data-protection obligation and should not be confused with a general deadline for resolving every payment dispute.
The NDPC has moved beyond public awareness campaigns to investigations and enforcement activities involving organisations that process personal information.
Its 2025 Annual Report disclosed that the Commission was handling multiple investigations into alleged privacy violations across several sectors, including banking and fintech.
The report identified account opening without the consent of data subjects as one of the concerns being investigated in the financial services sector. It noted that some financial institutions appeared to be opening accounts in the name of individuals without appropriate consent and said systemic efforts were underway to ensure that adequate authentication mechanisms were in place before customers were onboarded.
The Commission also identified unauthorised access to personal data as a major concern, noting that such breaches could involve careless access by employees or deliberate access for criminal purposes.
To strengthen accountability, the NDPC introduced a Standard Notice to Address Grievance, known as SNAG, to formalise the complaint process for individuals whose data protection rights have allegedly been violated.
The Commission also said it was transitioning towards full enforcement of the Nigeria Data Protection Act General Application and Implementation Directive 2025, with provisions covering compliance audits, data protection impact assessments and the responsibilities of data protection officers.
Its enforcement approach includes warnings, compliance orders and remedial fees, depending on the circumstances of each case.
The NDPC’s activities are significant because financial information can become a tool for fraud when personal data is improperly accessed, disclosed or processed. However, the Commission’s investigations into banking and fintech privacy violations should not be confused with investigations into every instance of electronic payment fraud. Its responsibility is primarily the protection of personal data and privacy rights.
For consumers, the connection between data protection and financial security is direct. Personal information that is poorly protected can provide criminals with the tools to impersonate customers, deceive them into authorising transactions or gain access to accounts.
The Economic and Financial Crimes Commission (EFCC) also has a role in tackling financial crimes, including electronic fraud. Its investigations, prosecutions and asset recovery activities are important parts of the wider response to cyber-enabled financial crime.
In September 2026, the EFCC announced that it had secured a final forfeiture order covering 431 mobile phones linked to Chinese cyber-fraud operators previously convicted by a Federal High Court in Lagos.
According to the Commission, the devices were connected to a cyber-fraud operation involving romance, investment and cryptocurrency scams. The investigation followed a sting operation conducted in December 2024, during which more than 700 individuals were arrested.
The EFCC said the court ordered the final forfeiture of the devices to the Federal Government after the Commission established their connection to unlawful activities.
The case demonstrates the Commission’s continued efforts to investigate organised cybercrime and secure assets connected to fraudulent operations. However, the forfeiture of devices should not be confused with the recovery and refund of money to individual victims of domestic bank-transfer fraud.
In August 2026, EFCC Chairman, Ola Olukoyede, also disclosed that the Commission had recovered assets and cash valued at approximately N1.233 trillion over 34 months, between October 2023 and July 2026.
He said N836.34 billion had been returned to individuals, corporate organisations and other beneficiaries, while approximately N397.26 billion went directly to the Federal Government and public institutions.
Although the figures demonstrate the scale of the Commission’s asset recovery activities, they cover different categories of financial and economic crimes and cannot be presented as money recovered specifically for victims of digital payment fraud.
The absence of a clearly disaggregated public dataset showing digital-payment fraud complaints investigated by the EFCC, funds frozen, recoveries made and amounts returned to individual victims makes it difficult to assess the direct impact of its interventions on consumers affected by fraudulent transfers.
For victims, arrests and convictions are important, but the ability to recover lost money remains a critical part of justice.
The issue of responsibility becomes even more complicated when a transaction involves more than one institution. A customer may initiate a transfer through one bank or payment platform, while the receiving account belongs to another institution. The sending institution may have to engage the receiving institution to trace the money, establish what happened and determine whether any funds remain available.
This creates a situation in which customers may be required to pursue several institutions before obtaining an explanation or resolution.
The concerns about consumer protection and accountability have also been echoed by Dr Stanley Jacob, President of the Fintech Association of Nigeria, who identified trust as a fundamental challenge confronting the country’s expanding digital payment ecosystem.
Speaking at the 2026 Conference of the Committee of Heads of Bank Operations in Lagos, Jacob said the growth in digital payment adoption had not removed consumers’ concerns about the safety and reliability of the system.
“Adoption has grown, but trust remains the fundamental issue in digital payments,” he said.
He noted that many customers still preferred to keep their money in traditional banks, using digital accounts mainly for transactions because of concerns about confidence. He also argued that physical bank branches remained important as places where customers could seek assistance and resolve disputes, even as digital-only financial institutions expanded.
“Nigerians treat bank branches like hospitals. You hope you never need them, but you cannot do without them in times of crisis,” Jacob said.
He called for stronger collaboration between banks and fintech companies, while identifying branches as potential centres for cybersecurity support, advanced authentication and verification of high-value transactions.
Similarly, the Chairman of the Lagos Chapter of the Association of Mobile Money and Bank Agents in Nigeria (AMMBAN), Mr Ibirogba Oluwagunwa, has raised concerns about the burden of failed electronic transactions on consumers, particularly users of USSD and agent banking services.
Oluwagunwa said consumers were bearing the consequences of transaction failures while the institutions providing the services were not doing enough to ensure prompt resolution.
“The consumer is suffering while others are enjoying the services,” he said.
Questioning the accountability process surrounding failed transactions, he asked: “When these transactions fail, where does the money stay? Who keeps it? Why does it sometimes take weeks before customers are refunded or not refunded at all?”
His concerns reinforce the need for clearer accountability among financial institutions, payment providers and other participants in the electronic payment chain, particularly where customers are debited without receiving the value for which they paid.
Despite the existence of complaint portals, dispute-resolution infrastructure, fraud monitoring systems, law enforcement investigations and data protection regulations, important gaps remain in the public information available on consumer redress.
While NIBSS reports fraud losses and potential losses prevented, the industry needs to publish more detailed information on how much money is subsequently recovered and returned to victims. Similarly, the CBN’s complaint statistics show complaints received and resolved, as well as refunds facilitated, but more detailed disclosures on digital payment fraud would help consumers understand how many cases resulted in actual recovery.
The EFCC’s enforcement figures demonstrate the scale of its activities, but the public needs more information about the proportion of digital-payment fraud victims who eventually receive restitution. The NDPC’s investigations into banking and fintech privacy violations are also important, but the outcomes of these investigations, including remedial actions taken against offending institutions, should be more accessible.
For payment providers, published fraud-reporting channels and security policies are necessary, but they should be accompanied by transparent information on complaint volumes, resolution times, disputed transactions and customer refunds.
These gaps are particularly important because a consumer who reports a failed transaction should not have to chase several institutions without knowing who owns the complaint. A customer who suspects an unauthorised debit should receive a proper investigation rather than a generic response. Where a transfer is reported as fraudulent, the institutions involved should have a clear process for communicating, tracing funds and explaining the outcome.
Requests for information and comment sent to the institutions contacted for this investigation had not received responses at the time of writing. The CBN’s publicly available regulations, circulars, guidelines and reports were therefore examined to establish the measures it has introduced and the obligations imposed on financial institutions. The published policies of some platforms were also reviewed to understand the complaint and fraud-reporting channels available to their customers. Their published procedures, however, do not independently establish how effectively individual complaints are resolved.
Ultimately, consumer protection cannot rest on educating customers to avoid clicking suspicious links, sharing their PINs or disclosing one-time passwords. Financial literacy and personal caution are necessary, but they cannot substitute for the responsibility of institutions that design, operate and regulate the payment infrastructure.
Nigeria’s digital payment ecosystem has made it easier to send and receive money, pay bills and conduct business. The country has also introduced regulations, fraud monitoring systems, dispute-resolution mechanisms and enforcement measures to strengthen the system.
The next test is whether these interventions can deliver equally dependable protection when things go wrong.
For Victoria, the unresolved N20,000 airtime transaction remains a reminder that the convenience of digital payments means little to a customer who cannot get a failed transaction reversed. For Ogoma, the challenge is not simply the loss she alleges but the difficulty of navigating the process she was told to follow.
As electronic payments become more deeply embedded in everyday life, the measure of a trusted system must be more than how quickly money moves. It must also be how effectively consumers are protected when it moves wrongly.
Image 12: Governor of the Central Bank of Nigeria (CBN), Olayemi Cardoso.
NDPC Image: National Commissioner of the Nigeria Data Protection Commission (NDPC), Dr Vincent Olatunji.
2.jpg: Managing Director and Chief Executive Officer of the Nigeria Inter-Bank Settlement System (NIBSS), Premier Oiwoh.
Image 13: Executive Director of the Consumer Advocacy and Empowerment Foundation (CADEF), Prof. Chiso Ndukwe-Okafor.