 Follow Us on Google

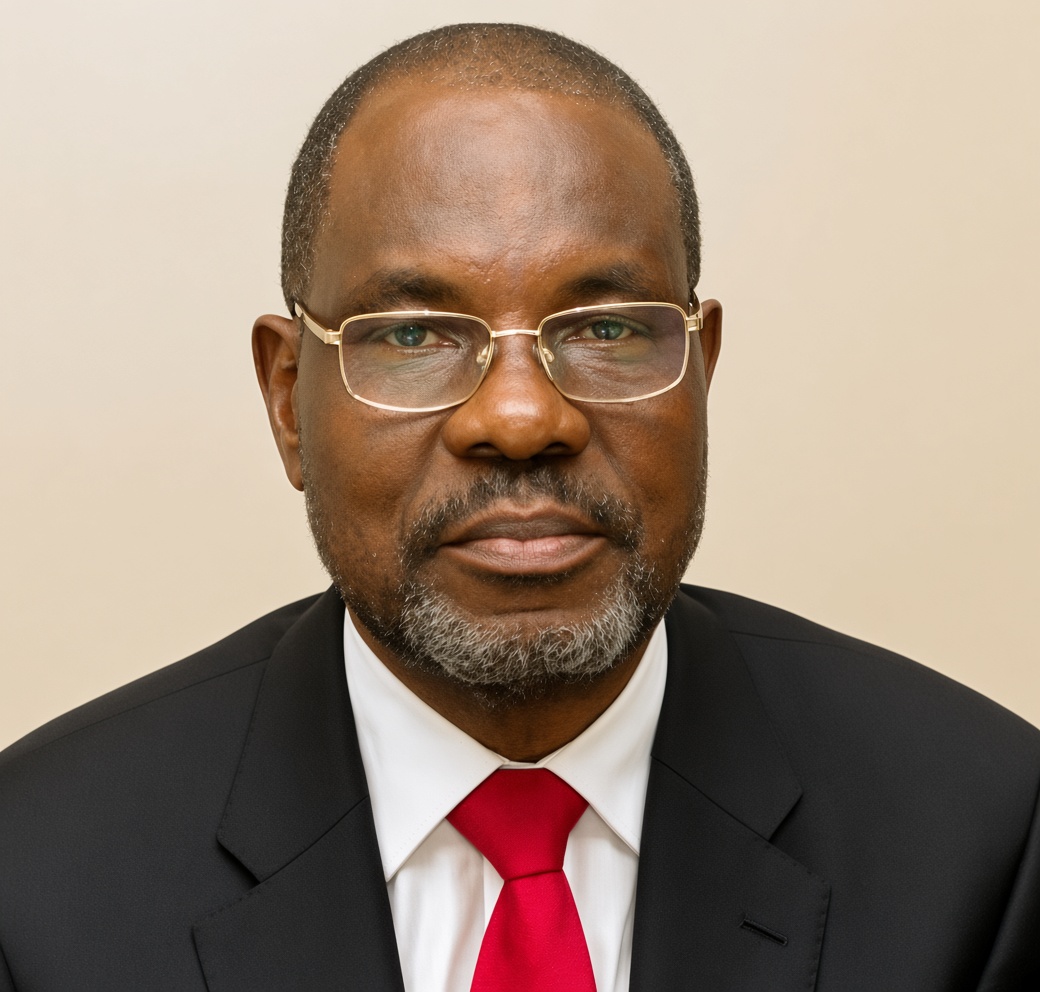
• Ex-MBAN president proposes digital property registry and mortgage-backed securities to unlock housing finance
_________________________________________________________________
From Juliana Taiwo-Obalonye, Abuja
Nigeria must increase its annual housing delivery to 500,000 units, from the current level of fewer than 50,000 formal housing units, if the country is to make meaningful progress in tackling its housing deficit, estimated at more than 17 million units.
To achieve this, the immediate past President of the Mortgage Banking Association of Nigeria (MBAN), Ebilate Mac-Yoroki, has called for a fundamental restructuring of the country’s housing finance system, including the mobilisation of pension funds, insurance assets and capital market investments to finance large-scale housing development.
Mac-Yoroki, who is also Chairman of CityCode Mortgage Bank Limited, said Nigeria could no longer depend on traditional government budgetary allocations and conventional bank lending to bridge its widening housing gap.
In a position paper dated November 4, 2026, and presented to stakeholders in the housing, capital markets and real estate sectors, he proposed a market-driven framework that would transform housing from a fragmented and high-risk investment into a standardised, transparent and investable asset class.
He identified two major structural problems undermining housing delivery in Nigeria: capital mismatch and information asymmetry. He argued that addressing both would unlock the long-term financing required to deliver 500,000 homes annually.
According to him, commercial banks are structurally constrained from providing affordable long-term mortgages because they depend largely on short-term deposits, typically of between 30 and 90 days, to finance loans that may run for 15 to 25 years.
He said the mismatch between short-term funding and long-term mortgage obligations had made it difficult for financial institutions to provide affordable housing loans at single-digit interest rates.
Mac-Yoroki proposed mobilising institutional funds from Pension Fund Administrators (PFAs), insurance companies and foreign portfolio investors to provide the patient capital needed to finance housing projects and long-term mortgages.
He recommended the use of Mortgage-Backed Securities (MBS), covered bonds and residential Real Estate Investment Trusts (REITs) to channel institutional investments into housing development.
Under the proposed arrangement, primary mortgage banks would pool and securitise their mortgage portfolios, enabling them to raise funds from institutional investors through the capital market, including the Nigerian Exchange (NGX).
He said the Nigeria Mortgage Refinance Company (NMRC) could serve as a liquidity refinancing platform, allowing mortgage banks to recycle funds and continuously originate new housing loans.
The former MBAN president also advocated the establishment of tax-efficient residential REITs and forward-purchase funds to guarantee developers an assured market for their properties before construction begins.
“This provides developers with guaranteed exit channels before construction begins, eliminating sales risk,” he stated.
He further recommended blended financing arrangements involving green bonds, social housing bonds and government-backed infrastructure bonds, supported by federal credit guarantees, to reduce the cost of financing.
Beyond funding, Mac-Yoroki identified the absence of a reliable, centralised property ownership and transaction database as another major obstacle to attracting investment into Nigeria’s real estate sector.
He proposed the establishment of a Central Housing Depository (CHD), modelled on the Central Securities Clearing System (CSCS), to create a unified digital platform for property ownership records, mortgages and existing claims on properties.
He observed that, unlike the capital market, where securities transactions are supported by structured digital clearing and settlement systems, land administration in Nigeria remains largely paper-based and decentralised.
The position paper estimated that more than 90 per cent of land in Nigeria remained unregistered, a situation he said encouraged multiple-sale fraud, prolonged title perfection and increased the risks associated with property transactions.
Other News
The proposed Central Housing Depository, he explained, would integrate state Geographic Information Systems (GIS) databases, facilitate digital property titling, enable real-time verification of property ownership and provide reliable information on existing mortgage claims.
According to him, the system could reduce title perfection processes from months to days while making property transactions more transparent and secure.
He also argued that a centralised housing database would make it easier for financial institutions to verify collateral, trade mortgage assets and use eligible property-backed instruments to access liquidity.
On housing market data, Mac-Yoroki called on MBAN to establish a consolidated national housing data repository to track mortgage originations, disbursements and loan performance across public intervention programmes, institutional financing arrangements and commercial mortgage banks.
He urged the Federal Ministry of Housing and Urban Development to establish an Inter-Agency Housing Data Directorate to work with the MBAN secretariat and ensure that government housing policies, land reforms and budgetary allocations are informed by reliable market data.
He said the availability of comprehensive housing data would also support automated credit scoring for informal-sector workers and the adoption of Automated Valuation Models (AVMs) to reduce reliance on subjective property valuations.
He maintained that accurate geographical demand data would help developers identify areas with genuine demand for affordable and middle-income housing, rather than continue concentrating investments in luxury properties.
On supply-side challenges, Mac-Yoroki identified land tenure complications, rising construction costs, inadequate infrastructure, high interest rates and cumbersome regulatory approvals as issues that must be addressed to achieve the 500,000-unit annual target.
He called for the harmonisation of state governors’ consent procedures under the Land Use Act, the adoption of digital land administration systems and the expansion of local manufacturing of building materials, including cement, steel and alternative construction inputs, to reduce exposure to foreign exchange volatility.
He also advocated public-private partnerships to finance roads, electricity and water infrastructure, noting that off-site infrastructure could account for between 20 and 30 per cent of total housing development costs.
To address affordability, he proposed single-digit interest rate subsidies and shared-equity schemes to enable low- and middle-income earners to access and repay long-term mortgages despite prevailing inflationary pressures.
He further called for the digitisation of municipal planning approvals through single-window clearance portals to reduce bureaucratic delays and accelerate housing construction.
Outlining a 36-month implementation roadmap, Mac-Yoroki proposed that the first 12 months should be devoted to developing regulatory guidelines for the Central Housing Depository in collaboration with the Securities and Exchange Commission (SEC), the Central Bank of Nigeria (CBN) and the Federal Ministry of Housing and Urban Development.
Between the 12th and 24th months, he proposed launching securitised residential mortgage-backed securities through NMRC’s liquidity framework and integrating state GIS databases into the proposed depository.
The final phase, covering months 24 to 36, would involve deploying forward-purchase REIT capital to finance large-scale residential developments and launching national Automated Valuation Models.
He said achieving 500,000 housing units annually would require moving beyond conventional government spending to a financing and regulatory system capable of attracting long-term domestic and international investment.
“Deepening capital markets creates the funding capacity, while a Central Housing Depository and standardised housing data provide the transparency, velocity and trust required to attract institutional capital at scale,” he stated.
Mac-Yoroki, who has over three decades of experience spanning capital markets, mortgage underwriting and housing policy, is a Fellow of the Chartered Institute of Stockbrokers and the Association of National Accountants of Nigeria. He is also a Director of NGX Regulation and an alumnus of Harvard Business School.