 Follow Us on Google

From Juliana Taiwo-Obalonye, Abuja
Nigeria must increase its annual housing delivery to 500,000 units if the country is to make meaningful progress in tackling its housing deficit, estimated at more than 17 million units.
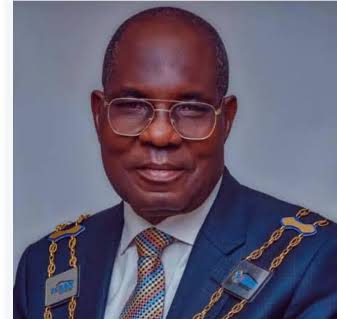
To achieve this, the immediate past President of the Mortgage Banking Association of Nigeria (MBAN), Ebilate Mac-Yoroki, called for a fundamental restructuring of the country’s housing finance system, including the mobilisation of pension funds, insurance assets, and capital market investments to finance large-scale housing development.
Mac-Yoroki, who is also Chairman of CityCode Mortgage Bank Limited, said Nigeria could no longer depend on traditional government budgetary allocations and conventional bank lending to bridge its widening housing gap.
In a position paper dated November 4, 2026, and presented to stakeholders in the housing, capital markets, and real estate sectors, he proposed a market-driven framework that would transform housing from a fragmented and high-risk investment into a standardised, transparent, and investable asset class.
He identified two major structural problems undermining housing delivery in Nigeria as capital mismatch and information asymmetry, arguing that addressing both would unlock the long-term financing required to deliver 500,000 homes annually.
Mac-Yoroki proposed mobilising institutional funds from Pension Fund Administrators (PFAs), insurance companies, and foreign portfolio investors to provide the patient capital needed to finance housing projects and long-term mortgages.
He recommended the use of Mortgage-Backed Securities (MBS), covered bonds, and residential Real Estate Investment Trusts (REITs) to channel institutional investments into housing development.
Other News
Under the proposed arrangement, primary mortgage banks would pool and securitise their mortgage portfolios, enabling them to raise funds from institutional investors through the capital market, including the Nigerian Exchange (NGX). He said the Nigeria Mortgage Refinance Company (NMRC) could serve as a liquidity refinancing platform, allowing mortgage banks to recycle funds and continuously originate new housing loans.
The former MBAN president also advocated the establishment of tax-efficient residential REITs and forward-purchase funds to guarantee developers an assured market for their properties before construction begins.
“This provides developers with guaranteed exit channels before construction begins, eliminating sales risk,” he stated.
He further recommended blended financing arrangements involving green bonds, social housing bonds, and government-backed infrastructure bonds, supported by federal credit guarantees, to reduce the cost of financing.
Beyond funding, Mac-Yoroki identified the absence of a reliable, centralised property ownership and transaction database as another major obstacle to attracting investment into Nigeria’s real estate sector.
He proposed the establishment of a Central Housing Depository (CHD), modelled after the Central Securities Clearing System (CSCS), to create a unified digital platform for property ownership records, mortgages, and existing claims on properties.
He urged the Federal Ministry of Housing and Urban Development to establish an Inter-Agency Housing Data Directorate to work with the MBAN secretariat and ensure that government housing policies, land reforms, and budgetary allocations are informed by reliable market data.