 Follow Us on Google


- Cuts global growth outlook to 3.1% as energy costs mount
From Uche Usim, Bangkok, Thailand
The International Monetary Fund (IMF) has called on the federal government to provide targeted cash transfers and temporary income support to vulnerable households struggling with rising food and energy costs.
The Fund said the measures would help reduce poverty and improve food security, but stressed that they must be backed by a credible plan to strengthen government revenue and ensure public funds are spent effectively.
It also projected global economic growth of 3.1 per cent this year but warned that rising energy and commodity prices, mounting public debt and uncertainties surrounding artificial intelligence (AI) are putting the world economy under pressure.
The Fund said global growth was expected to rise to 3.4 per cent in 2027, but warned that risks remained tilted to the downside, with further disruptions capable of weakening economic activity and pushing inflation higher.
These come as the IMF noted that resilience of the global economy is reaching its limits as rising energy and commodity prices, mounting debt and uncertainty over artificial intelligence threaten growth, with developing economies such as Nigeria facing heightened risks.
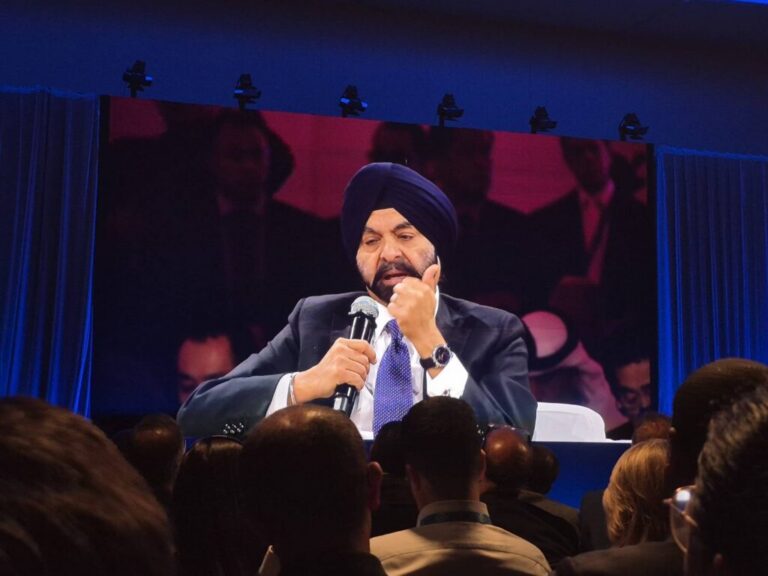
Chief of the IMF Research Department’s World Economic Studies Division, Deniz Igan, made the call during a press briefing on the Fund’s October 2026 World Economic Outlook at the IMF/World Bank Annual Meetings in Bangkok, Thailand on Tuesday.
She said food and energy security were critical to addressing the rising cost of living in Nigeria and other developing economies.
“In this environment, we advocate cash transfers and targeted, temporary income support for the most vulnerable households in Nigeria,” Igan said.
She added: “Such transfers can help reduce poverty and improve food security. This should be accompanied by a credible medium-term fiscal framework. That framework should focus on improving the quality of public expenditure and strengthening revenue collection.”
Igan stressed that increased spending to support vulnerable households must go hand in hand with better revenue collection to ensure that government finances remained sustainable.
The IMF’s recommendation comes amid persistent pressure on Nigerian households from high food prices, energy costs and other essential expenses, despite the country’s position as a major oil producer.
Speaking on how monetary policy should respond to an oil price shock that is not driven by rising demand, the Fund’s Economic Counsellor and Director of Research, Silvana Tenreyro, said central banks faced a difficult balance between controlling inflation and protecting economic activity.
She explained that when oil prices rise without an increase in demand, inflation could worsen even as economic activity slows, making it more difficult for central banks to decide how aggressively to tighten monetary policy.
According to her, monetary authorities must keep inflation on a path towards their targets, usually within two to three years, while considering the damage higher interest rates could cause to economic activity.
She said the appropriate response would depend on each country’s circumstances, including its existing inflation rate, labour market conditions and exposure to higher energy prices.
Tenreyro further said the Nigerian government needed to address the rising cost of essential goods, particularly food and energy, while ensuring that vulnerable households did not bear a disproportionate share of the burden.
“These are essential items and their prices have risen significantly. The question is how to address these pressures while ensuring that the burden does not fall disproportionately on vulnerable households,” she said.
Tenreyro described Nigeria as a clear example of the difficulties facing energy-exporting countries, where higher oil earnings do not necessarily translate into affordable living costs for citizens.
Although economic growth had held up, she said many Nigerians continued to suffer from food insecurity and the high cost of essential goods.
The IMF’s position comes as the Fund warned in its latest global outlook that rising energy and commodity prices, mounting public debt and uncertainty surrounding artificial intelligence (AI) were putting the resilience of the global economy under pressure.
It projected global economic growth of 3.1 per cent in 2026, with risks tilted to the downside.
The Fund warned that further energy supply disruptions could weaken growth and push inflation higher, while a possible correction in AI-related investments could affect financial markets and economic activity beyond the technology sector.
For Nigeria, higher international oil prices could increase export earnings and government revenue but also raise domestic fuel, transport and production costs, putting additional pressure on households and businesses.
The Fund urged governments to strengthen public finances, improve the quality of spending and build financial buffers to withstand future economic shocks.
The IMF and World Bank Group Annual Meetings are holding in Bangkok from October 12 to 18, bringing together policymakers, central bank governors, financial institutions and business leaders to discuss global economic and development challenges.