 Follow Us on Google

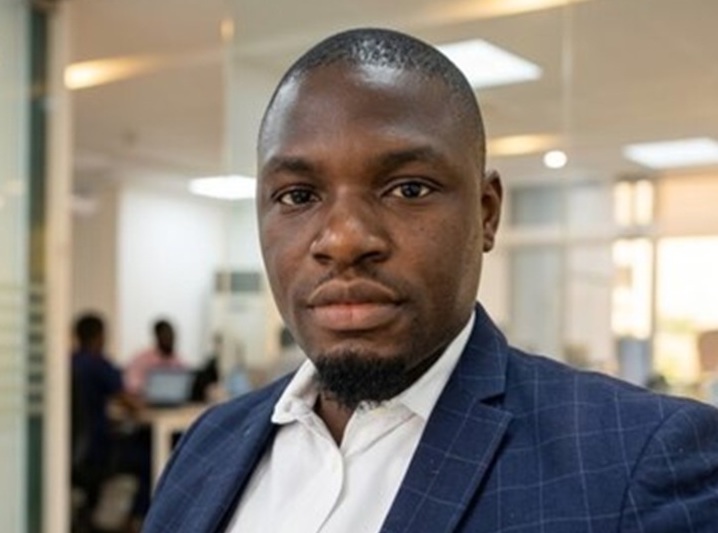
As digital banking expands in Nigeria, financial institutions have been urged to strengthen consumer protection, transparency and responsible lending practices to sustain public trust in technology-driven financial services.
James Edeh, Head of Compliance at FairMoney Microfinance Bank, said compliance must go beyond meeting regulatory requirements to become a core part of product development, customer service and business operations.
Edeh, who made the call in an article on consumer protection in tech-enabled banking, said the growing use of technology to deliver payments, savings and credit services had increased the need for financial institutions to protect customers’ funds, personal information and financial interests.
According to him, while technology is making financial services more accessible and convenient, sustainable growth in the sector will depend on how effectively institutions manage risks and uphold customer confidence.
He cited data from Enhancing Financial Innovation and Access (EFInA), which showed that formal financial inclusion among Nigerian adults increased from 56 per cent in 2020 to 64 per cent in 2023, while 26 per cent remained financially excluded.
Edeh said the figures highlighted the opportunities technology offered to expand access to financial services, but stressed that such expansion must be accompanied by safeguards that ensure fair treatment of customers.
He noted that customers needed clear information about financial products, appropriate handling of personal data, transparent disclosure of charges and reliable channels for resolving complaints.
According to him, compliance should be integrated into financial institutions’ operations from the early stages of product development rather than treated as a corrective measure after regulatory breaches occur.
“Compliance can no longer be understood solely as an internal function concerned with meeting regulatory requirements. In a technology-enabled financial system, it is increasingly part of the architecture of consumer protection,” he said.
He added that decisions relating to data management, product design, lending practices and customer communication had direct implications for consumer protection.
Edeh particularly stressed the need for responsible lending as technology-enabled financial institutions expand their reach and develop new ways to assess borrowers.
Other News
He said wider access to credit must be supported by clear disclosure of loan terms, applicable charges and other material conditions, alongside responsible handling of customers’ information.
He also called for effective complaint-resolution mechanisms to enable customers to seek redress when problems arise.
The FairMoney executive said the evolving consumer protection landscape in Nigeria reflected increasing expectations for transparency, fairness, responsible business conduct and data protection across digital financial services.
He noted that fintech companies and microfinance banks must balance commercial growth with the obligation to protect customers, adding that appropriate compliance frameworks should support innovation rather than unnecessarily restrict it.
Edeh said FairMoney Microfinance Bank, which is licensed and regulated by the Central Bank of Nigeria (CBN), operates within a prudential framework designed to support the safety and soundness of the financial system.
He added that consumer protection responsibilities also extend to compliance with applicable laws and regulatory requirements, including those issued by the CBN and, where applicable, the Federal Competition and Consumer Protection Commission (FCCPC).
According to him, eligible deposits held with the bank are insured by the Nigeria Deposit Insurance Corporation (NDIC), subject to the applicable coverage limits and conditions.
He maintained that the long-term success of digital banking would depend not only on technological innovation but also on the strength of governance and the commitment of financial institutions to safeguarding customers.
“Customers may be attracted initially by convenience, speed or access. Their longer-term confidence, however, will depend on whether institutions demonstrate consistency, transparency and a clear commitment to protecting their interests,” he said.
Edeh added that although technology was changing how banking services were delivered, the fundamental relationship between financial institutions and their customers remained anchored on trust.