 Follow Us on Google

By Rita Okoye
Demand for digital credit in Nigeria has surged, yet most applicants are rejected and 28.8 million adults remain outside the financial system. A 2024 study co-authored by Ann Kinyanjui argues that lenders do not have to choose between making money and reaching the unbanked.
Nigeria’s loan apps promised to bank the unbanked. For many of the people who need them most, the answer is still no.
The appetite for digital credit is not in doubt. By September 2024, Nairametrics reported, the number of lenders approved by the Federal Competition and Consumer Protection Commission had climbed to 320, up from 284 just four months earlier, and lenders said loan applications had quadrupled within the year. Yet one lender, KwikPay Credit, said its system rejected about 4,500 of every 5,000 applications almost instantly.
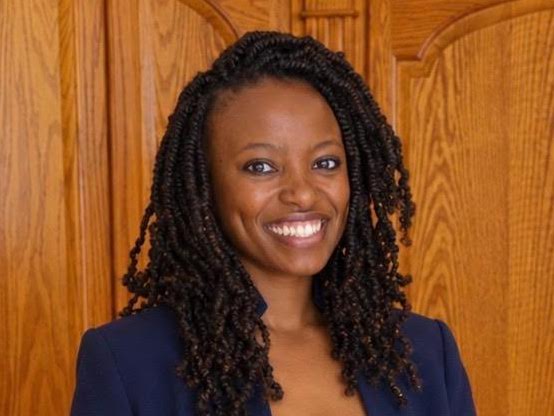
Kenyan finance expert Ann Kinyanjui says that gap between demand and approval is the central problem facing digital lending in Africa.
“Turning away nine out of ten applicants may protect a lender’s balance sheet, but it pushes millions of Nigerians back to informal moneylenders. The real question is not whether to lend to low-income borrowers, but how to do it responsibly and still make money,” said Ms Kinyanjui, a Cornell University MBA candidate and experienced Corporate Finance leader, speaking in a personal capacity.
Her view draws on a 2024 paper she co-authored, “Advances in Digital Lending Profitability and Financial Inclusion Strategies in Emerging Markets,” published in the International Journal of Scientific Research in Computer Science, Engineering and Information Technology. Ms Kinyanjui is the second of five authors. The study examines how digital lenders in markets such as Nigeria, Kenya and Ghana price risk and control costs, and how they can reach informal traders, rural households and young people with no credit history. It argues that profitability and inclusion need not pull in opposite directions.
The stakes are high. The Access to Financial Services survey by Enhancing Financial Innovation and Access (EFInA), released in 2024, found that 74% of Nigerian adults were financially included in 2023, up from 68% in 2020. That still left 28.8 million adults, or 26%, outside the formal system. Only 6% of adults used credit. Exclusion stood at 37% in rural areas against 17% in cities, and at 47% in the North West.
The industry has also had to clean up its reputation. After widespread complaints about harassment and the misuse of borrowers’ phone contacts, the FCCPC introduced the Limited Interim Regulatory/Registration Framework and Guidelines for Digital Lending in 2022. Google then required loan apps serving Nigeria to show FCCPC approval to remain on its Play Store from January 31, 2023. By September 2024, according to Nairametrics, 88 apps were on the Commission’s watchlist and 47 had been removed from the Play Store.
Other News
Of the 320 approved lenders, 264 held full FCCPC approval, 42 had conditional approval and 14 were licensed by the Central Bank of Nigeria. Many still relied on very small, short-term “nano” loans of N3,000 to N5,000 at high interest rates, products that are costly to run and prone to default.
Ms Kinyanjui argues the answer lies in better information, not fewer loans.
“The tools already exist. Mobile money records, utility payments and transaction histories can tell a lender far more about a trader’s ability to repay than a payslip ever could. When lenders design products around irregular incomes, women, who run so many of Nigeria’s small businesses, are among the first to benefit,” she said.
The gender point is backed by the data. EFInA found the gap between men and women in financial inclusion widened from 8 to 9 percentage points between 2020 and 2023.
Ms Kinyanjui has spent more than seven years in corporate finance. Before moving to the USA for her MBA at Cornell University, she led finance, administration, and operations at Hallmark Advertising and Marketing, a pan-African firm, where she says she cut annual financing costs from $300,000 to $75,000 by restructuring short-term debt. While there, she also initiated corporate social responsibility programmes that supplied sanitary towels to more than 24,900 schoolgirls and diapers to more than 81,900 new mothers.
She is a Certified Public Accountant registered in Kenya and a Fellow of the Institute of Management Consultants of Nigeria, and has written widely on banking risk, credit analytics and corporate finance.
Nigeria’s digital lenders have shown they can attract millions of applicants. Ms Kinyanjui believes the next test is whether they can say yes to more of them safely.
“Regulation and inclusion are not enemies. Clear rules weed out bad actors and build the trust that responsible lenders need to grow. Nigeria has a real chance to show the rest of Africa what profitable, inclusive digital credit looks like,” she said.