 Follow Us on Google

…AfricaNenda warns trust, consumer protection gaps could slow adoption
By Chinenye Anuforo from Mauritius
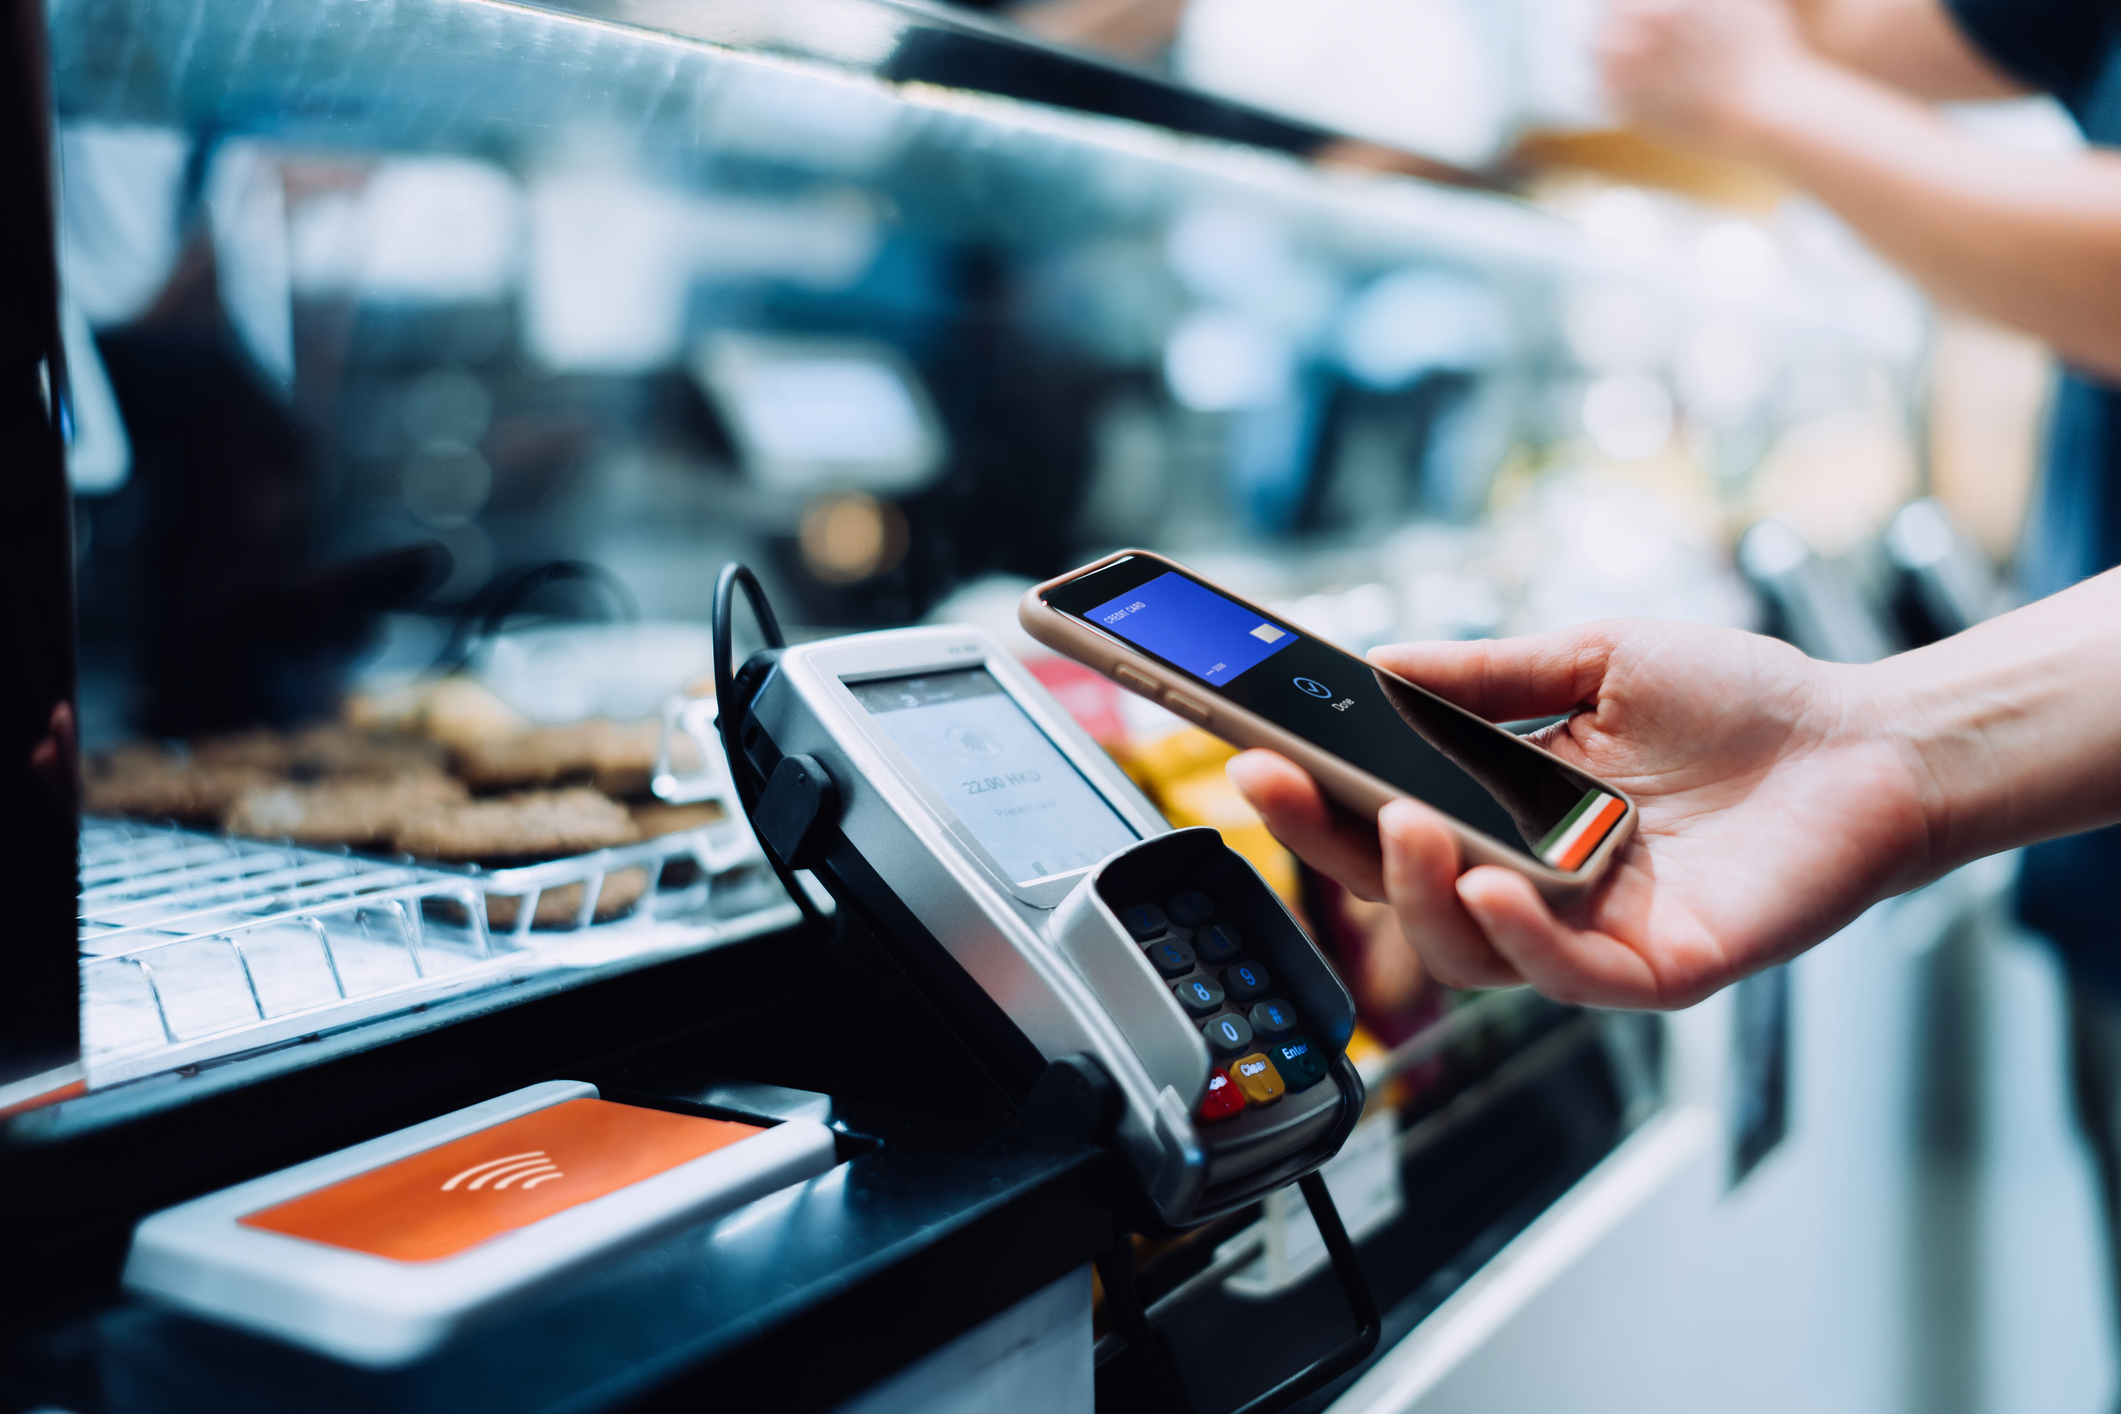
Nigeria’s instant payment system has earned the highest inclusivity rating in Africa, even as the continent recorded 71.4 billion instant payment transactions valued at $1.8 trillion in 2025, according to the 2026 State of Inclusive Instant Payment Systems (SIIPS) in Africa report.
The fifth edition of the report, released today, Thursday, November 19, 2026, in Mauritius by AfricaNenda Foundation in partnership with the United Nations Economic Commission for Africa (UNECA) and the World Bank Group, identifies Nigeria’s NIBSS Instant Payment (NIP) system as the only one on the continent to have attained the mature level of inclusivity, the highest category on the report’s inclusivity spectrum.
The report’s assessment highlighted the country’s progress in developing an instant payment infrastructure that supports transactions across different financial service providers, including banks and mobile money operators.
It also noted that NIP is helping to reduce the cost of digital payments for Nigeria’s largely informal micro, small and medium enterprises (MSMEs) by eliminating some of the expenses associated with holding funds in advance and reconciling transactions.
The continental figures reflect the rapid expansion of instant payment infrastructure across Africa. According to the report, the 71.4 billion transactions recorded in 2025 represent almost three times the volume processed in 2021, with a total transaction value of $1.8 trillion.
As of July 2026, Africa had 39 live instant payment systems, comprising 35 domestic and four regional systems, providing instant payment functionality across 43 countries.
However, despite the impressive growth, the report warns that persistent trust and consumer protection challenges could undermine the continent’s efforts to move more people and businesses away from cash.
Findings from a survey of 1,403 individuals and MSME digital payment users across 15 African markets between March and April 2026 showed that 55 per cent of respondents still relied on cash for about half of their transactions, while only 33 per cent used digital payment methods most of the time.
More than half of the respondents had experienced payment problems, including delayed transactions and transfers to wrong recipients. Yet, one in three users who encountered such problems did not report them, largely because they did not know how to seek redress.
The report further found that 43 per cent of users who lost money in digital payment transactions reduced their use of digital payment services.
It said the experience of failed transactions and unresolved complaints could weaken confidence in digital financial services, even where the underlying payment infrastructure was efficient.
According to the report, trust is influenced by the speed of transactions, clear payment confirmation messages and the ability of users to verify recipients before sending money.
Deputy Chief Executive Officer of AfricaNenda Foundation and lead author of the report, Sabine F. Mensah, said the continent had made significant progress in expanding instant payment infrastructure, but the next phase must focus on building public confidence.
“Five years ago, our first report mapped 29 instant payment systems. Today, there are 39, and one in two African adults live in a country served by an inclusive instant payment system,” she said.
Mensah said the priority had shifted from simply making instant payments available to ensuring that people trusted the systems enough to use them instead of cash.
“The question has changed. It is no longer whether Africans can pay instantly, but whether they trust the system enough to stop reaching for cash,” she said.
She added that confidence depended on transactions going through instantly, preventive safeguards such as recipient name validation, real-time payment confirmation and timely resolution of complaints when something went wrong.
Chief Executive Officer of AfricaNenda Foundation, Dr Robert Ochola, said Africa had developed inclusive instant payment infrastructure at a remarkable pace, driven by the expertise of its local technology professionals.
“Africa has built inclusive instant payment infrastructure at remarkable speed, drawing on the talent of its own software engineers and designers,” he said.
He stressed that the next five years should focus on making the systems affordable, safe and sustainable.
The report called for stronger consumer protection measures, including recipient verification, real-time transaction confirmation and accessible complaint-resolution mechanisms.
It also recommended clearer frameworks for determining liability in cases of authorised push payment fraud, alongside stronger use of artificial intelligence to detect and prevent fraudulent transactions.
For Nigeria, the findings underline the importance of building on the NIP system’s strong inclusivity rating by strengthening safeguards that protect users when digital transactions fail or funds are lost.
The report’s broader assessment suggests that the success of instant payment systems should not be measured only by the number or value of transactions processed, but also by whether users can transact confidently and obtain timely redress when problems occur.
It also found that countries with instant payment systems recorded about seven percentage points higher active account usage than countries without such systems, although the report described the finding as an early, directional association rather than proof of a direct causal relationship.
With Nigeria already recognised for the maturity of its instant payment infrastructure, the next challenge is ensuring that reliability, affordability and consumer protection keep pace with the growth of digital transactions.